5 Market Signals Investors Use to Read Cyclical vs Defensive Sectors
By MarketCapLens · Published · 7 min read
Cyclical sectors rise and fall with the economy, while defensive sectors hold up because demand for their products barely changes in a downturn. Investors lean toward cyclical names like retailers, banks, and industrials when growth is accelerating, and shift toward defensive names like utilities, staples, and health care when growth slows or a recession looks likely. The rest comes down to reading sector data correctly and knowing which group tends to lead at each stage of the cycle.
TL;DR:
- Defensive stocks outperform during shocks by an average of 9.5%, but they still tend to decline less than the market in downturns.
- Sector classification varies, with energy often treated as defensive in MSCI’s framework but considered cyclical by many practitioners.
- Sector leadership shifts predictably through four phases, from cyclicals leading in early recovery to defensives dominating during recessions.
- Monitoring macro indicators and sector ratios monthly helps investors time rotations more effectively than reacting to daily news.
- Frequent, current sector data tracking enhances the ability to identify genuine shifts and avoid false signals during complex market cycles.
MarketcaplensTrack Sector Trends With Current DataMarketCapLens brings together current share prices, sector breakdowns, historical data, and market trends across more than 2,500 public companies.Explore MarketCapLens
Table of Contents
- What Are Defensive Stocks and How Do They Behave?
- Which Sectors Count as Cyclical vs Defensive?
- How Do These Sectors Behave Across the Business Cycle?
- How Do Investors Actually Use This Framework?
- Where Does the Cyclical/Defensive Framework Break Down?
- How MarketCapLens Helps You Track Sector Leadership
- A Market View Worth Sitting With
- See Live Sector Data Without the Guesswork
- Sources
What Are Defensive Stocks and How Do They Behave?
Defensive stocks sell things people buy regardless of the economy: electricity, toothpaste, prescription drugs. Demand stays steady because these purchases aren’t optional, so revenue and earnings swing far less than the broader market. That stability tends to show up as lower beta, more consistent dividends, and smaller drawdowns during recessions.
Sectors commonly labeled defensive include:
- Consumer staples — food, beverages, household goods
- Utilities — electric, gas, and water providers
- Health care — pharmaceuticals, insurers, hospital operators
- Telecommunication services — wireless and broadband carriers
Data point: across four separate oil-price shocks, defensive stocks outperformed the broader market by an average of 9.5%. Even in the 2022 Russia-Ukraine shock, defensive shares posted negative absolute returns, yet they still outperformed the market by a modest margin. That’s the pattern that matters: defensive sectors don’t guarantee gains, but they tend to lose less when everything else is falling.
Which Sectors Count as Cyclical vs Defensive?
MSCI’s widely used framework splits the market into two camps. MSCI classifies Consumer Discretionary, Financials, Industrials, Materials, and Information Technology as cyclical, and Consumer Staples, Health Care, Utilities, and Telecommunication Services as defensive. Energy sits in an odd spot in MSCI’s scheme, grouped with defensives in that framework even though most practitioners treat it as one of the more cyclical corners of the market given its sensitivity to global demand.
Here’s how the ten major sectors typically break down in practice:
| Sector | Typical classification | Notes |
|---|---|---|
| Consumer Discretionary | Cyclical | Retail, autos, travel |
| Financials | Cyclical | Banks, insurers, asset managers |
| Industrials | Cyclical | Manufacturing, machinery, transports |
| Materials | Cyclical | Chemicals, mining, metals |
| Information Technology | Cyclical (mixed) | Hardware/semis cyclical; software steadier |
| Consumer Staples | Defensive | Food, beverages, household products |
| Health Care | Defensive | Pharma, insurers, providers |
| Utilities | Defensive | Electric, gas, water |
| Telecommunication Services | Defensive | Wireless, broadband |
| Energy | Split by source | Cyclical demand, but grouped defensive by MSCI |
A few sectors resist clean labels. Technology hardware and semiconductors swing hard with capital spending cycles, but enterprise software with recurring subscription revenue behaves closer to defensive. Financials often track credit cycles closely, yet a company with a heavy fee-based, asset-management model can be more stable than a regional bank loaded with commercial loans. When you’re unsure where a stock fits, check its revenue mix and earnings sensitivity rather than trusting the sector label alone, a point echoed in Fidelity’s sector rotation guidance. You can browse live sector weightings and constituent lists on MarketCapLens’s sector hub if you want to see how these groupings shake out among the largest companies right now.
How Do These Sectors Behave Across the Business Cycle?
Sector leadership rotates in a fairly predictable sequence, though the timing varies each cycle. Fidelity’s business-cycle framework breaks it into four phases:
- Early recovery: Cyclicals lead hard. Consumer discretionary, industrials, and financials tend to outperform as credit loosens and confidence returns.
- Mid cycle: Leadership broadens. Technology and industrials often keep working while growth is steady and predictable.
- Late cycle: Energy and materials frequently take over as inflation pressures build and input costs climb.
- Recession: Defensives dominate. Utilities, staples, and health care hold up while cyclical earnings get cut.
To read a cyclical-to-defensive ratio chart, watch the line’s direction, not just its level. A rising ratio means cyclicals are outpacing defensives, generally a sign of risk appetite and economic confidence. A falling ratio signals investors are rotating toward safety, often ahead of weaker data. The line rarely moves in a straight line, and sharp reversals within a few weeks are common around earnings season or Federal Reserve meetings.
It’s worth knowing that both groups can rally at once. BlackRock’s 2026 commentary described a stretch where cyclicals and defensives both outperformed a narrow group of mega-cap technology leaders simultaneously, a reminder that rotation isn’t always a binary bet between two camps. Falling bond yields can lift defensive dividend payers for income reasons at the same moment an improving growth outlook lifts industrials and banks. Treat the ratio as one input, not a standalone signal.
How Do Investors Actually Use This Framework?
Sector rotation isn’t about guessing the next headline. It’s about tracking a handful of indicators that tend to move before sector leadership shifts, then sizing positions modestly around what you see.
- Watch payroll trends and the yield curve. Weakening job growth or a flattening/inverting curve often precedes a shift toward defensives.
- Track credit spreads. Widening high-yield spreads usually signal rising recession risk and falling risk appetite.
- Follow earnings revisions. Analysts cutting cyclical earnings estimates faster than defensive ones is an early rotation tell.
- Check market breadth. A narrowing rally, where fewer stocks are driving index gains, often precedes defensive leadership.
- Size the tilt, don’t bet the portfolio. A 5 to 10 percentage-point shift in sector weighting is a tilt; doubling your cyclical exposure is a bet.
For implementation, sector ETFs remain the simplest vehicle, letting you adjust exposure without picking individual winners inside a sector. Rebalance on a schedule rather than reacting to every headline, and confirm any rotation signal with at least two indicators before acting, a discipline Fidelity’s own research recommends over relying on sector labels alone.
Pro Tip: Run the check monthly, not daily. Compare the cyclical/defensive ratio over 3-, 6-, and 12-month windows, then confirm the trend with two macro indicators before shifting a single dollar, a routine MarketCapLens has outlined in detail.
Where Does the Cyclical/Defensive Framework Break Down?
Defensive doesn’t mean risk-free. Utilities and staples carry real interest-rate sensitivity: when yields rise sharply, their dividend payouts look less attractive next to bonds, and share prices can fall even while earnings stay stable. Valuation matters too. A defensive stock trading at a stretched price can still lose money even if the underlying business performs exactly as expected.
Cyclical exposure can also hide inside companies that don’t look cyclical on paper. A “tech” company with hardware sales tied to corporate capital budgets behaves very differently than one selling subscription software with contracted renewals, even though both sit in the same GICS bucket.
Before acting on any sector signal, run through a short checklist:
- Quality: Does the company have pricing power and consistent margins?
- Balance-sheet strength: Can it service debt if revenue drops?
- Valuation: Are you paying a reasonable price relative to earnings and growth?
- Macro confirmation: Do at least two independent indicators support the rotation thesis?
Bernstein’s research frames this as checking for quality, stability, and price, or QSP, before treating any stock as genuinely defensive. Investors managing sequence-of-returns risk near retirement should apply the same scrutiny to cash buffers and fixed income, a concern covered well in Amberwealth’s guide to managing that risk.
How MarketCapLens Helps You Track Sector Leadership
Reading sector rotation in real time requires current data, not a quarter-old snapshot. Sector data with breakdowns and performance metrics updated multiple times daily makes spotting an emerging rotation far easier than pulling numbers from scattered sources.
A simple workflow for readers who want to monitor this themselves:
- Check current sector rankings and weightings on the MarketCapLens sectors page.
- Compare performance across 3-, 6-, and 12-month windows to spot a developing trend rather than short-term noise.
- Browse specific groups, like the largest consumer defensive companies or consumer cyclical companies, to see which individual names are driving sector moves.
A Market View Worth Sitting With
Most retail investors treat sector rotation as a light switch: risk-on or risk-off. It’s rarely that clean. The 2026 stretch where cyclicals and defensives both outpaced concentrated tech leadership is proof that rigid rules break down, and the investors who benefit most are the ones checking sector data regularly rather than reacting to one headline. Watching the ratio, not predicting it, is the actual edge.
— MarketCapLens
See Live Sector Data Without the Guesswork
Reading rotation signals from a monthly brokerage statement puts you weeks behind. Sector rankings and performance metrics updated frequently across thousands of companies help ensure the cyclical-to-defensive picture reflects current market conditions.
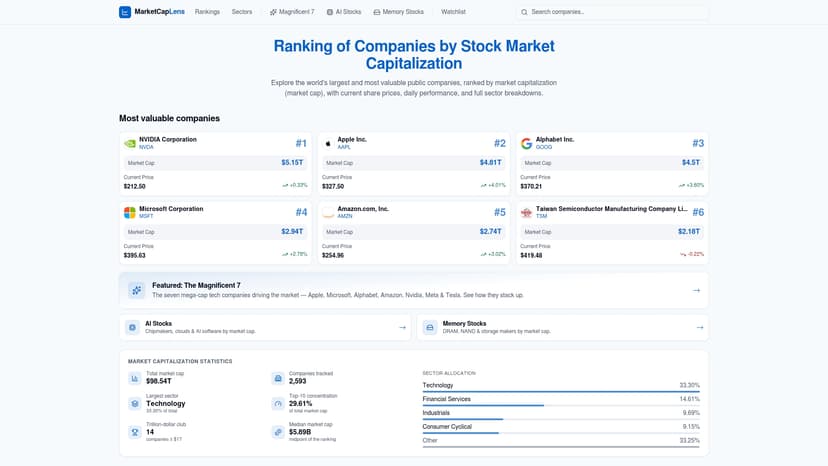
If you’ve been trying to eyeball sector strength from scattered ticker quotes, that gap closes fast once you have one dashboard tracking the numbers. Start on the market cap rankings page to see how the ten major sectors are performing right now, or dig into a specific group like what a sector actually is if you’re still building out the fundamentals. Either way, check the rankings before your next rebalancing decision rather than after.
Sources
- MSCI Cyclical and Defensive Indexes
- Defensive stocks: A potential antidote to inflation shocks (Bernstein/AdvisorAnalyst)
- Sector rotation strategies (Fidelity)
- The odd couple of 2026: cyclicals and defensives (BlackRock)
Recommended
For informational purposes only and is not investment advice. Do not rely on the facts, figures, ticker symbols, or other statements in this article — they may be incomplete, outdated, or incorrect, and we are not responsible for errors. See our disclaimer.