Run Live Data Checks to Reveal Market Concentration Risk for Investors
By MarketCapLens · Published · 13 min read
Market concentration is elevated by historical standards, but that alone does not mean you need to sell anything today. The right first move is measurement, not reaction: calculate your top ten holdings’ combined weight and check for overlap across the funds you already own. Online tools can pull that data in minutes, giving you a real starting point before you decide whether to adjust.
TL;DR:
- Measure your portfolio’s top ten holdings and the Herfindahl-Hirschman Index to gauge concentration levels accurately rather than relying solely on visible weights.
- Since 2015, market-cap weighted indexes have become more concentrated due to rising mega-cap stock weights and sector rallies, especially in technology and semiconductors.
- Concentration increases short-term volatility and can cause larger losses during downturns, especially for regulated funds limited by diversification rules.
- Comparing overlapping holdings across your funds reveals hidden risks, as multiple funds often hold the same large-cap stocks, intensifying exposure.
- Sector concentration risks are uneven, with technology more prone to company-specific risks, while energy and materials are influenced more by commodity cycles.
MarketcaplensMeasure Market Concentration ClearlyTrack market capitalization, share prices, historic data, and sector breakdowns across more than 2,500 public companies.Explore MarketCapLens
Table of Contents
- What market concentration risk actually means
- Why concentration has climbed since 2015
- How concentration shows up in your returns and drawdowns
- How to measure concentration in your own portfolio
- Strategies to manage concentration without overreacting
- How MarketCapLens helps you run these checks
- Lessons from past episodes of high concentration
- How regulators approach concentration risk
- Where concentration risk is highest by sector
- Concentration risk and the broader question of systemic risk
- Balancing concentration concerns with long-term goals
- Start measuring your exposure with MarketCapLens
- Sources
- FAQ
What market concentration risk actually means
Market concentration describes how much of a market’s total value sits in a small number of companies. Concentration risk is what happens to your portfolio when that imbalance works against you: a handful of names driving most of your gains can also drive most of your losses.
Professionals quantify this with a few tools. The Herfindahl-Hirschman Index (HHI) goes further by squaring each holding’s weight and summing them, capturing the full distribution rather than just the top slice. HHI converts into an “effective number of stocks,” a way of asking how many equally-weighted positions would produce the same concentration.
The S&P 500’s effective number of stocks fell significantly from before the pandemic to today, meaning the index behaves more like a portfolio with fewer stocks than its full listing, according to State Street’s analysis, suggesting a notable reduction in diversification.
Numbers worth tracking in your own portfolio:
- Combined weight of your ten largest positions (CR10).
- HHI across all holdings, translated into effective number of stocks.
- Sector weight versus a broad benchmark like the S&P 500.
Why concentration has climbed since 2015
Several forces have pushed concentration higher rather than lower over the past decade. Passive indexing plays a mechanical role: as a stock’s price rises, its weight in a market-cap-weighted index rises automatically, and new inflows into index funds buy proportionally more of the biggest names. Sector-specific rallies have compounded this. The surge in AI-related stocks and semiconductor and cloud names concentrated returns in a small group of mega-caps rather than spreading gains broadly.
Fund rules add another layer. When a benchmark concentrates, the diversification limits many funds must follow become binding, forcing mechanical trims that can themselves distort short-term prices.
Between 2015 and 2024, the share of the ten largest U.S. stocks in total market capitalization rose notably, increasing from a low teens percentage to nearly one-third, according to NBER research.
Key drivers to watch:
- Market-cap weighting mechanically compounds gains in already-large stocks.
- Sector leadership cycles, such as the recent run in technology and semiconductor names, concentrate returns further.
- Regulatory diversification thresholds can force trims that amplify short-term volatility once they bind.
How concentration shows up in your returns and drawdowns
Concentration does not just raise everyday volatility, it changes how a portfolio behaves in a downturn. A handful of dominant stocks can carry an index higher for years, then contribute disproportionately to losses when sentiment turns, because the same names that drove the gains represent an outsized share of the exposure.
Regulated funds face a specific version of this problem. Many funds must satisfy the 50/5/10 diversification test, which limits how much any single issuer can represent. As benchmark concentration rose, this rule became binding for more funds, and constrained funds that had to trim large positions showed measurable short-term performance drag in the months following the constraint binding, according to NBER’s analysis of fund concentration effects.
Passive investors inherit this dynamic whether they intend to or not. Goldman Sachs Asset Management notes that index funds replicate benchmark concentration automatically, so an investor who believes they are broadly diversified by owning an S&P 500 fund may hold a much narrower effective bet than the fund’s name suggests.
Practical implications:
- Everyday volatility can look manageable even as tail risk builds underneath it.
- Constrained funds may underperform temporarily right when they are forced to rebalance.
- A passive allocation is only as diversified as its underlying benchmark, not as diversified as its holding count implies.
How to measure concentration in your own portfolio
You do not need institutional tools to get a clear read on concentration. A structured check takes less than an hour and gives you a number to act on rather than a feeling to react to.
- Calculate your top ten weight. Add up the percentage of your total portfolio held in your ten largest positions and compare it to a benchmark like the S&P 500’s current CR10.
- Compute HHI and convert to effective number of stocks. Square each holding’s weight as a decimal, sum the results, then divide 1 by that sum to get your effective number, a lower number means tighter concentration.
- Run an overlap check across funds. Pull the top holdings of every fund and ETF you own and flag any stock that appears in more than one, since overlapping funds can hide concentration that looks diversified on paper.
- Check position size against liquidity and risk tolerance. A large position in a thinly traded stock carries different risk than the same weight in a mega-cap, so weigh both before deciding whether to trim.
Pro Tip: Run the overlap check first. It usually reveals more hidden concentration than the top-N calculation alone, especially for investors who own several thematic or sector funds.
FINRA’s guidance on concentration risk puts this plainly: investors should look under the hood of the funds they own, because holding multiple funds that each hold the same large-cap names does not reduce risk the way it appears to.
Strategies to manage concentration without overreacting
Managing concentration is less about eliminating it and more about setting rules before you need them. A written rebalancing discipline, target bands around key positions or sectors with a set review frequency, keeps decisions consistent and removes the temptation to chase or panic-sell. Tax-aware rebalancing, using new contributions to fill underweight areas rather than selling appreciated winners outright, can achieve the same end with a smaller tax bill.
On the diversification side, several tactics work together rather than as substitutes for one another:
- Add exposure to small-cap and international stocks, which tend to move differently than mega-cap domestic names.
- Consider equal-weight or factor-based funds, which reduce the mechanical weighting problem built into cap-weighted indexes.
- Use a sector rotation approach if you want active exposure management rather than a static allocation.
- Hold fixed income, gold, or cash as ballast, sized to your time horizon and need for stability rather than as a market call.
Not all concentration deserves the same response. MIT Sloan research points out that large, dominant companies can be inherently more diversified internally, across products, geographies, and revenue streams, than smaller ones, so concentration in genuinely strong businesses is not automatically a red flag. The more useful question is whether the concentration reflects durable fundamentals or a speculative run that has outpaced them.
Pro Tip: Separate the decision to rebalance from the decision to sell a conviction holding. You can trim a position back to a target band without abandoning the thesis that got you there.
How MarketCapLens helps you run these checks
Running the measurement steps above is faster with live data in front of you rather than building it from scratch. Some platforms track market capitalization, sector allocation, and historical performance across thousands of listed companies, updated multiple times daily, which covers most of what the checks above require.
Practical ways to use it:
- Pull current top-ten index weights and compare them against your own portfolio’s CR10.
- Check sector breakdowns to see how concentrated your holdings are relative to a broad benchmark.
- Compare top holdings across the Magnificent Seven or other mega-cap groups to spot overlap between funds you own.
- Review historical market cap data to see how quickly a position’s weight has grown, a signal that a rebalance may be due.
Lessons from past episodes of high concentration
Concentration has spiked and receded before, and each episode left a similar lesson: dominance built on durable fundamentals tends to persist longer than dominance built on narrative alone. The late 1990s technology run concentrated market value in a small group of internet and telecom names whose valuations outpaced their earnings, and the subsequent decline hit the most concentrated portfolios hardest because the same stocks that had driven gains made up an outsized share of exposure on the way down.
A similar pattern played out with financial stocks heading into 2008, when concentrated exposure to a sector facing a common structural weakness, rather than to a single company, amplified losses across portfolios that looked diversified by holding count but were not diversified by risk factor. The common thread across these episodes is that concentration risk rarely announces itself through the metric investors watch most closely, price performance. It shows up in how correlated the losses are when sentiment shifts.
This is why regulators and fund managers increasingly emphasize measurement tools like HHI and overlap checks rather than relying on headline weight alone. A portfolio can look diversified by number of holdings while behaving like a much smaller, more concentrated one when the underlying names move together. The practical takeaway for today’s environment, where mega-cap technology names carry a historically large share of index weight, is not that history is repeating exactly, but that the mechanism, concentrated gains followed by concentrated losses, has recurred enough times to warrant regular measurement rather than assumption.
How regulators approach concentration risk
Regulatory attention to concentration risk is longest-standing in banking, where the Office of the Comptroller of the Currency requires banks to identify, measure, monitor, and control concentrated credit exposures as a matter of safety and soundness, with dynamic limits rather than static caps. The logic transfers directly to investment portfolios: concentration itself is not prohibited, but it has to be tracked and managed deliberately.
For registered funds, the mechanism is the 50/5/10 diversification test, which limits how much of a fund’s assets can sit in any single issuer once that issuer crosses certain thresholds. As benchmark concentration has risen, this test has become binding for a growing number of funds, forcing trims that can create short-term price pressure on the affected stocks. This is a structural feature of how concentration and fund regulation interact, not a prediction about any specific stock.
For individual investors, there is no equivalent binding rule, which puts the responsibility for measurement and action on you rather than on a compliance framework. FINRA’s investor guidance reflects this by focusing on practical steps: look under the hood of the funds you own, check for overlapping exposures, and diversify across and within asset classes rather than assuming a fund’s name or category guarantees diversification.
Where concentration risk is highest by sector
Concentration risk is not evenly distributed across the market. Technology has carried the largest share of recent index-level concentration, driven by a small number of companies whose market capitalization dwarfs the rest of the sector, a dynamic visible in current sector rankings. This matters because an investor who feels diversified by owning a broad technology fund may still hold a portfolio dominated by two or three companies’ fortunes.
Energy and basic materials tend to show a different pattern: concentration there is often driven by commodity cycles rather than individual company dominance, so the risk is more sector-wide and cyclical than company-specific. Financials carry their own version of concentration risk, tied less to market capitalization and more to shared exposure to interest rates, credit conditions, and regulatory changes, which is why financial-sector downturns have historically hit seemingly diversified portfolios harder than expected.
The practical lesson is that sector concentration checks need to look past the label. A fund or portfolio described as “diversified technology” can still carry meaningful single-stock risk if two or three names dominate its weight, while a portfolio spread across several sectors can still carry hidden concentration if those sectors share an underlying risk factor, such as sensitivity to interest rates or a single input commodity.
Concentration risk and the broader question of systemic risk
Concentration in individual portfolios connects to a larger question about the stability of markets as a whole. When a small number of companies represent an outsized share of major indexes, the fortunes of pension funds, retirement accounts, and institutional portfolios become more tied together than their diversification-by-holding-count would suggest, because so many of them are exposed to the same handful of names through index funds and benchmark-tracking strategies.
Recent research quantifies this link directly. An increase in market concentration, measured by HHI, has been found to correspond to an increase in 1% Value-at-Risk, with the effect becoming stronger during high-volatility periods, according to a 2026 econometric study. on the relationship between concentration and financial fragility. That finding suggests concentration does not just raise risk within an individual portfolio, it can amplify tail risk across the market during periods of stress, when correlated selling in a handful of dominant names moves the entire index more than the same event would have moved a less concentrated market.
This is part of why regulators treat concentration as a systemic concern and not just a portfolio-management detail. A market where a handful of companies drive most of the index’s return also means that shocks to those companies, whether from earnings disappointments, regulatory action, or sector-specific stress, can transmit through index funds, pension allocations, and benchmark-linked products faster and more broadly than a similar shock in a less concentrated market.
Balancing concentration concerns with long-term goals
Concentration often reflects genuine business success, not a warning sign by itself. The useful discipline is measuring exposure regularly and asking whether your reasons for holding a position still hold, not reacting to headlines about index weight. Document your thresholds in advance, then let the numbers, not the news cycle, trigger action.
— MarketCapLens
Start measuring your exposure with MarketCapLens
These platforms track market cap rankings, sector breakdowns, and historical performance across many companies, updated multiple times daily, providing the raw numbers behind the checks described above.
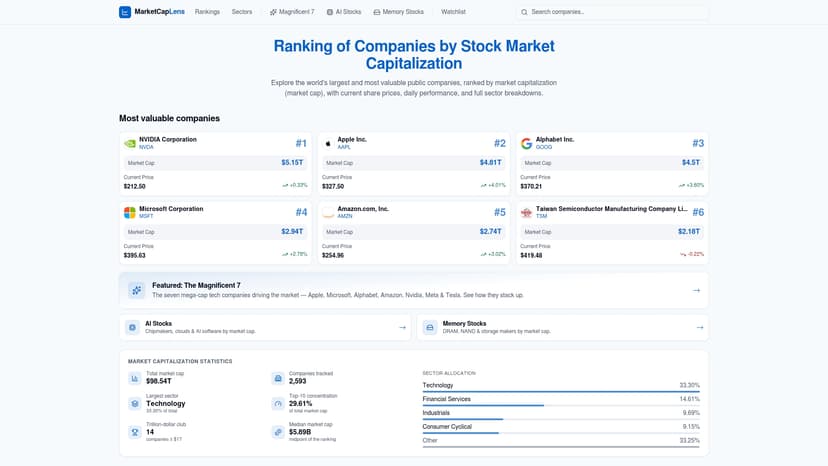
Start with the market cap rankings to check your top holdings’ combined weight, or read the plain-English guide to market capitalization if you want the fundamentals before you run the numbers.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- FINRA — Concentration risk
- NBER working paper — effects of fund concentration and constraints (w35007.rev1)
- F1000Research — The concentration-fragility nexus (2026)
- SSGA — Concentration is up; diversification isn’t gone
FAQ
Is market concentration good or bad for investors?
Neither by default: concentration can reflect genuine strength in dominant companies, but it also raises the chance that a downturn in a few names hits your whole portfolio at once. MIT Sloan research notes that large companies can be internally diversified, so the right response depends on whether the concentration is backed by fundamentals.
What are the main types of market risk investors face?
Market risk generally includes concentration risk, volatility from broad price swings, liquidity risk when positions are hard to sell without moving the price, and systemic risk from shocks that spread across the whole market. Concentration risk stands out because it can turn an otherwise manageable market move into an outsized portfolio loss.
What does concentration risk mean in investing?
Concentration risk is the added danger that comes from having too much of your portfolio tied to a small number of stocks, sectors, or issuers. FINRA recommends diversifying across and within asset classes and reviewing fund holdings directly to catch concentration that is not obvious from the outside.
What does “market concentration” mean at the index level?
Market concentration describes how much of a market’s total value sits in its largest companies rather than being spread evenly across all constituents. It is commonly measured using top-N weights, the Herfindahl-Hirschman Index, or the effective number of stocks, which SSGA’s analysis shows has fallen sharply for major indexes in recent years.
Recommended
For informational purposes only and is not investment advice. Do not rely on the facts, figures, ticker symbols, or other statements in this article — they may be incomplete, outdated, or incorrect, and we are not responsible for errors. See our disclaimer.