See Live Holdings: MSCI vs S&P Methodology, 503 vs 600–650 for Pros
By MarketCapLens · Published · 13 min read
MSCI builds indexes through largely rules-based screens that produce broader constituent coverage with a mild mid-cap tilt, while S&P blends eligibility criteria with committee judgment and, for its ESG products, layers an optimizer on top of S&P Global CSA scores. The practical result is a family of small but persistent differences: slightly different sector weights, occasional tracking divergence between funds that claim to track “the market,” and fee gaps that can matter more than either firm’s methodology once you hold a position for years.
TL;DR:
- MSCI includes roughly 600 to 650 names covering about 85% of the US market, whereas the S&P 500 maintains exactly 503 constituents with committee discretion.
- MSCI’s quarterly reviews and semiannual reconstitutions lead to more frequent composition changes, often driven by numeric thresholds rather than qualitative judgment.
- S&P’s index committee considers qualitative factors and sector balance, making additions and removals less predictable and less tied to strict numeric thresholds.
- MSCI’s ESG ratings are industry-relative and based on key issues most relevant to each sector, while S&P’s ESG scores result from an optimizer targeting industry-specific decarbonization and diversification.
- Fee differences can matter more than methodology, with MSCI tracker fees around 0.09% and S&P 500 funds typically around 0.03%, affecting long-term costs significantly.
MarketcaplensCompare Market Data More ClearlyMarketCapLens brings together live prices, market capitalizations, sector breakdowns, and historical data for thousands of public companies.Explore MarketCapLens
Table of Contents
- At-a-glance comparison of index construction and ESG scoring
- How MSCI builds and maintains its index
- How S&P builds and maintains its flagship indices
- MSCI ESG Ratings: key issues, governance, and industry-relative scoring
- S&P Global CSA and how S&P DJI builds ESG indices
- What these differences mean for tracking, factor exposure, and cost
- A decision checklist for choosing a benchmark or index family
- Seeing the differences in live holdings and sector weights
- When methodology actually changes the decision
- Use MarketCapLens to compare index exposures directly
- Sources
- FAQ
At-a-glance comparison of index construction and ESG scoring
Before getting into the mechanics, it helps to see where the two approaches actually diverge. The differences are not cosmetic. They show up in constituent counts, how often the index changes, and how each firm decides what counts as a good ESG score.
- Constituent count and coverage: MSCI USA holds roughly 600 to 650 names and targets around 85% of U.S. free-float market capitalization, while the S&P 500 holds exactly 503 constituents by design (a handful of companies carry multiple share classes).
- Selection method: MSCI applies quantitative size, liquidity, and free-float screens with limited discretion; S&P uses eligibility rules as a first filter, then a committee makes the final call on additions and removals.
- Weighting and rebalancing: Both use float-adjusted market-cap weighting, but MSCI runs quarterly reviews with semiannual full reconstitutions, while S&P rebalances quarterly under committee oversight.
- ESG scoring architecture: MSCI ESG Ratings score companies on an industry-relative seven-band scale built from a handful of material key issues; S&P’s ESG index products score companies through the Corporate Sustainability Assessment and then run an optimizer to hit industry-level coverage and carbon targets.
Each of these threads matters more or less depending on whether you are picking a passive core holding, building a factor tilt, or evaluating an ESG-labeled fund against its stated objective.
How MSCI builds and maintains its index
MSCI’s process starts from an eligibility universe defined by market size, price, and liquidity, then applies a free-float adjustment so that only shares actually available to investors count toward a company’s weight. Shares held by governments, founders, or other strategic holders in a way that restricts trading are excluded from the float calculation, which means two companies with identical total market capitalization can end up with different index weights.
Once a company clears the eligibility screens, its inclusion is essentially mechanical. There is no committee vote weighing qualitative factors such as sector representativeness or public profile. That rules-based discipline is why MSCI USA typically includes more names than the S&P 500. Companies that meet MSCI’s size and liquidity bar but never get selected by S&P’s committee (often smaller, less well-known mid-cap names) end up inside MSCI USA’s roughly 600 to 650 constituents but outside the S&P 500’s 503.
MSCI reviews its indexes quarterly and performs full reconstitutions twice a year, in May and November, when it reassesses the entire eligible universe against current size and liquidity thresholds. Quarterly reviews handle smaller updates like corporate actions and rapid market-cap shifts between full reconstitutions. This cadence means MSCI USA’s composition can shift meaningfully twice a year as newly qualifying mid-caps enter and shrinking names drop out, which creates turnover that a purely capitalization-weighted, buy-and-hold investor does not control.
That turnover has a second-order effect worth flagging: because additions and removals are triggered by objective thresholds rather than discretionary timing, MSCI’s rebalancing dates are predictable well in advance, which some index-linked funds and quantitative desks use to anticipate flow-driven price pressure around reconstitution windows. The tradeoff is that MSCI’s mechanical approach can occasionally add or drop a company purely because it crossed a numeric line, even when nothing about the business changed. Readers who want to see how free-float adjustments actually move a real company’s weight can check how the MarketCapLens ranking works for a plain walkthrough of the math.
How S&P builds and maintains its flagship indices
The S&P 500’s defining feature is not a formula. It is the S&P Dow Jones Indices Index Committee, a group that applies published eligibility rules (market capitalization minimums, adequate liquidity, positive recent earnings, U.S. domicile, and sufficient public float) but retains discretion over which qualifying companies actually get added and when. That discretion is why the index has held 503 constituents rather than a round 500 for some time: several member companies maintain dual share-class structures that each get counted separately.
Weighting inside the S&P 500 works the same way it does at MSCI: float-adjusted market capitalization determines each company’s share of the index, so restricted or closely held stock does not inflate a company’s weight. Rebalancing happens quarterly, in March, June, September, and December, with the committee reviewing candidates against the eligibility criteria at each cycle and making changes effective ahead of the next trading session.
The committee structure is the real point of departure from MSCI. A qualifying company is not automatically added just because it clears the numeric bar. The committee weighs sector balance, the likelihood a company remains viable, and whether an addition would create excessive turnover, among other qualitative considerations that are never fully codified in the published criteria. That judgment layer smooths out some of the noise that comes from pure rules-based screening; a company that briefly dips below a threshold because of a one-quarter earnings miss is less likely to be yanked out reflexively. It also means two analysts reading the same eligibility document can reasonably disagree about what the committee will do next, something that almost never happens with MSCI’s calendar-driven process.
MSCI ESG Ratings: key issues, governance, and industry-relative scoring
MSCI ESG Ratings score companies on a seven-band scale from AAA down to CCC, and the single most important thing to understand about that scale is that it is industry-relative rather than absolute. A AAA rating means a company leads its industry peer group on the issues that matter for that industry, not that it outperforms every company in every sector. Comparing a AAA-rated bank to a AAA-rated oil producer on an absolute basis misreads what the rating is actually measuring.
The rating is built from a curated set of Key Issues drawn from a universe of 33 Environmental and Social topics. MSCI selects between two and seven of those 33 issues for each company based on which ones are financially material to its specific sub-industry: water stress and land use for an agriculture company, data security and privacy for a technology platform, and so on. That selectivity is deliberate. It keeps the scoring focused on issues that plausibly affect the business rather than diluting the score with irrelevant metrics.
Governance is scored separately through a dedicated governance pillar covering six key issues, using a deduction-based model: companies start from a baseline and lose points for specific weaknesses in areas like board structure, pay practices, ownership and control, and accounting behavior. Controversies (fines, spills, labor violations, and similar events) feed into the relevant key issue score directly rather than sitting as a separate penalty. All of this rolls up into a single industry-normalized score, which MSCI then maps to the seven-band letter rating. The industry adjustment is what allows the final rating to function as a peer comparison tool rather than a blunt cross-sector scorecard.
S&P Global CSA and how S&P DJI builds ESG indices
S&P’s ESG scoring starts somewhere different: the Corporate Sustainability Assessment, an annual survey-based process run by S&P Global’s Sustainable1 unit that collects company-reported data across environmental, social, and governance dimensions, then maps responses to an industry-adjusted materiality framework so a utility and a software company are judged against different weighted criteria. The output is a single S&P Global ESG Score used as the raw input for S&P DJI’s ESG index construction.
Building an ESG index from that score is where S&P’s process diverges most sharply from a simple “buy the highest scorers” approach. S&P DJI selects constituents to reach industry-level float-adjusted market-cap coverage targets, often around 75% of each GICS industry group’s market capitalization, then applies exclusions before finalizing weights. Excluded categories typically include specific business involvements (tobacco, controversial weapons, thermal coal among common screens), companies flagged for UN Global Compact non-compliance, and companies tied to significant controversies.
The last step is the one that most distinguishes S&P’s ESG indices from a straightforward score-and-select model: an optimizer reweights the remaining constituents to minimize active share against the parent index while enforcing decarbonization targets, sometimes a reduction of roughly 30% in weighted average carbon intensity. The optimizer also removes the highest carbon-intensity weights and enforces diversification rules such as minimum and maximum position sizes, so no single reweighting decision creates an outsized bet. The result is a “glass-box” index designed to look and behave like its parent benchmark while shifting exposure away from carbon-intensive and poorly scored names, a very different philosophy from MSCI’s key-issue, industry-relative letter grade.
What these differences mean for tracking, factor exposure, and cost
The mid-cap names that MSCI includes and S&P’s committee tends to leave out create a real, if modest, factor difference between the two benchmarks. A fund tracking MSCI USA will typically carry a bit more small and mid-cap exposure than an S&P 500 fund, which shows up as slightly higher volatility in some periods and slightly better participation in mid-cap rallies in others. Neither effect is large enough to override an investor’s core allocation decision, but it is large enough to explain small, persistent return gaps between funds that both claim to track “the broad U.S. market.”
Fees frequently matter more than methodology. A MSCI USA tracker charging around 0.09% versus an S&P 500 fund charging closer to 0.03% creates a gap that compounds steadily: on a $5 million position, that six-basis-point spread costs roughly $3,000 a year before any difference in actual index performance is even considered. For most taxable or institutional allocators, that fee drag deserves at least as much scrutiny as the underlying constituent list.
Reconstitution timing carries its own cost. MSCI’s semiannual reconstitutions and S&P’s quarterly committee-driven changes both create predictable windows when index funds must buy and sell to match the new composition, and large flows around those dates can create short-term price pressure, particularly in additions with smaller trading volumes. Institutional desks that manage large index-linked positions often time trades around these windows deliberately. Fund wrappers, replication method (full replication versus optimized sampling), and tax-loss harvesting flexibility all interact with these mechanics in ways that matter more for large or actively managed allocations than for a buy-and-hold retail position. A primer on reading market cap without falling into common traps is useful background before comparing any two benchmarks directly.
A decision checklist for choosing a benchmark or index family
Match the benchmark to the mandate, not the other way around. Run through this sequence before committing capital or selecting a fund:
- Define your coverage objective: do you want the broadest reasonable market-cap footprint (MSCI’s approach) or the most widely recognized, committee-vetted large-cap benchmark (the S&P 500)?
- Decide your tolerance for discretionary decisions: rules-based screening is predictable and mechanical; committee selection introduces judgment that is harder to model in advance.
- Weigh fee sensitivity against methodology preference, since expense-ratio gaps between comparable funds often exceed the return impact of the underlying index choice.
- Check your turnover tolerance, since MSCI’s semiannual reconstitutions and S&P’s quarterly committee reviews both generate rebalancing trades that carry tax and market-impact consequences.
- If the objective is ESG-specific, confirm whether you need MSCI’s industry-relative letter rating or S&P’s optimizer-constructed, carbon-target-aware index, since the two answer different questions.
Pro Tip: Before trusting any ESG index label, read the provider’s own methodology document for the specific fund, not a marketing summary, since the exclusion list and optimizer constraints vary meaningfully between products carrying the same “ESG” name.
Seeing the differences in live holdings and sector weights
The cleanest way to see MSCI and S&P’s methodology differences at work is to compare live holdings rather than read about them abstractly. A platform tracks thousands of companies with sector breakdowns updated multiple times a day, which makes two comparisons straightforward to run: pull the top 10 holdings by market cap for the technology and health care sectors and check how many mid-cap names appear only outside the S&P 500’s list, then compare aggregate sector weights across sector rankings to see where MSCI’s broader coverage adds weight that the S&P 500 does not carry. Running both comparisons side by side, using current sector data rather than a static snapshot, shows the mid-cap tilt and sector-weight drift discussed above as concrete numbers rather than a theoretical effect. Readers building factor-aware allocations can start from the AI stocks market-cap rankings to see how a fast-moving sector gets weighted differently once mid-cap names enter or leave the eligible universe.
When methodology actually changes the decision
Methodology differences matter most at scale: a fund replicating an index for billions of dollars feels reconstitution timing and mid-cap tilt in ways a small individual position never will. For factor-aware allocation or manager due diligence, reading the methodology document is not optional. For most other decisions, fees and tracking history tell you more than the selection rules do.
— MarketCapLens
Use MarketCapLens to compare index exposures directly
Reading a methodology document tells you how an index is built. Checking live holdings and sector weights tells you what that construction actually produced this week. A platform tracks thousands of companies with sector breakdowns and company-level pages updated multiple times daily, which makes it a practical way to verify the mid-cap tilt or sector-weight gap you just read about instead of taking it on faith.
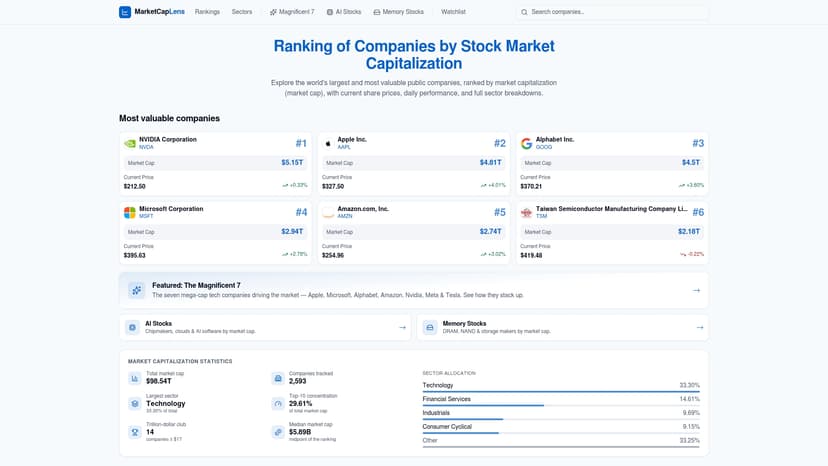
If you are comparing a specific fund against its benchmark, start with a company you already know, like RTX, Meta Platforms, or Palantir Technologies, and work outward to the sector level. Visit MarketCapLens to run your own market-cap and sector comparisons before your next allocation decision. For readers digging into reconstitution timing and how index-linked flows move prices around rebalancing windows, the fair value gap explainer from TradeDupe offers useful trading-side context.
Sources
- MSCI ESG Ratings methodology (excerpt)
- A Deep Dive into Sustainability Sector Indices (S&P DJI)
- MSCI USA vs S&P 500: 85% US Market Coverage | FATFIRE™
FAQ
Is MSCI better than S&P for index investing?
Neither is categorically better: MSCI USA offers broader coverage and a small mid-cap tilt through rules-based screening, while the S&P 500 offers a more concentrated, committee-vetted large-cap benchmark. The right choice depends on whether your mandate calls for maximum coverage or the most widely tracked large-cap reference point.
What is MSCI’s index methodology?
MSCI builds indexes using quantitative size, liquidity, and free-float screens applied consistently across an eligible universe, with quarterly reviews and semiannual full reconstitutions. MSCI USA holds roughly 600 to 650 constituents covering about 85% of U.S. free-float market capitalization, with limited discretionary input compared to committee-based approaches.
What is S&P’s index methodology?
The S&P 500 combines published eligibility rules (market cap, liquidity, profitability, and domicile criteria) with final selection decisions made by the S&P Dow Jones Indices Index Committee. That committee structure is why the index holds 503 constituents rather than exactly 500, since several members carry multiple listed share classes.
What is the difference between MSCI USA and the S&P 500?
MSCI USA includes more constituents, roughly 600 to 650 versus the S&P 500’s 503, because its rules-based screens capture mid-cap names that clear MSCI’s thresholds but were never selected by S&P’s committee. Both use float-adjusted market-cap weighting, but MSCI reconstitutes on a fixed semiannual schedule while S&P’s quarterly changes reflect ongoing committee judgment.
Recommended
For informational purposes only and is not investment advice. Do not rely on the facts, figures, ticker symbols, or other statements in this article — they may be incomplete, outdated, or incorrect, and we are not responsible for errors. See our disclaimer.