How 15 Minutes' Delay Costs Traders: Real Time vs End of Day Data
By MarketCapLens · Published · 9 min read
If your decisions happen while markets are open, you need a real-time feed. If your work happens after the close, EOD data usually does the job for less money. Most traders end up paying for both: a live feed for execution and EOD history for research and backtesting. Tools like MarketCapLens fill the gap in between, giving you a refreshed market-cap and daily-close snapshot without a streaming subscription.
TL;DR:
- Real-time data updates within milliseconds to seconds, essential for day traders and scalpers executing within the market hours.
- End-of-day data summarizes each trading session into OHLC, volume, and adjustments, ideal for long-term analysis and backtesting across decades.
- Combining streaming feeds with historical data helps refine intraday strategies while minimizing costs by matching data precision to trading style.
- Most retail platforms rely on the consolidated tape, which aggregates quotes and trades from all exchanges, sufficient for average investors.
- MarketCapLens provides refreshed daily market cap and price snapshots, suitable for casual monitoring and confirming daily closing data without a streaming subscription.
Marketcaplensmarketcaplens.comTrack Market Trends With ContextMarketCapLens brings refreshed prices, market caps, sector breakdowns, and historical data together for clearer daily market analysis.Explore MarketCapLens
Table of Contents
- Real-Time vs EOD Data: What Real-Time Actually Delivers
- What End-of-Day Data Is and When It’s Enough
- Intraday vs EOD: Matching Data Tier to Trading Style
- What Upgrading Your Data Plan Actually Buys You
- Where Consolidated Market Data Actually Comes From
- Backtesting on EOD: What It Can and Can’t Tell You
- Combining Real-Time Streams With Historical Context
- How MarketCapLens Fits Into a Real-Time and EOD Workflow
- Three Rules of Thumb for Choosing Your Data Tier
- Check Daily Closes and Sector Context Before You Upgrade
- Sources
- FAQ
Real-Time vs EOD Data: What Real-Time Actually Delivers
Real-time market data streams every quote, trade, and order-book change as it happens on the exchange. It comes in layers, and the layer you pay for determines how much of the market you actually see.
- Level 1 gives you the best bid and ask plus the last trade price, which is enough for most single-stock monitoring.
- Level 2 adds market depth, showing the stacked bids and offers behind the top of book.
- Time and sales logs every executed trade in sequence, which scalpers use to read momentum tick by tick.
These feeds travel through exchange direct feeds, the consolidated tape (more on that below), or vendor WebSockets and REST APIs that repackage the same data for retail platforms. A real-time feed always has latency, the transport time between the trade happening and your screen showing it, but it carries no deliberate offset. That’s a different thing from a delayed feed, which intentionally holds back a snapshot, commonly by 15 minutes, regardless of how fast the pipes are.
What End-of-Day Data Is and When It’s Enough
EOD data compresses an entire trading session into one row per security: open, high, low, close, and total volume, often with a split and dividend adjusted close layered on top for historical continuity.
- Standard fields: OHLC, volume, and session date.
- Adjusted close for accurate long-term return calculations.
- Corporate action flags (splits, dividends, halts) in more complete datasets.
The official record for the US equity market, Daily TAQ, is built after the closing bell and typically lands the same evening, usually between 8:30 PM and 10:00 PM Eastern. That archive stretches back to 1993, which is exactly why EOD data dominates backtesting: decades of clean, low-volume history at a fraction of the storage and licensing cost of tick data. If your strategy holds positions for days or weeks, EOD advantages, cheaper access, simpler files, and a deep archive, usually outweigh anything intraday granularity would add.
Intraday vs EOD: Matching Data Tier to Trading Style
The comparison boils down to four variables: freshness, cost, data volume, and how the data reaches you.
| Factor | Real-time | EOD |
|---|---|---|
| Freshness | Milliseconds to seconds | End of session |
| Typical cost | Subscription, often tiered by exchange | Free to low-cost |
| Data volume | Every tick and quote change | One row per session |
| Delivery | WebSocket, streaming API | REST, flat file, CSV |
Day traders and scalpers live and die by the first row of that table. A few hundred milliseconds of lag can turn a good entry into a bad fill, so real-time streaming with a direct or low-latency vendor feed isn’t optional.
Swing and position traders can usually run on EOD data alone, since their entries and exits don’t depend on intraday noise. Where EOD fails them is gap risk. A stock that moves sharply between one close and the next open won’t show up until the next daily bar.
Long-term investors rarely need anything faster than daily closes, which is why checking a company’s market cap and sector context once a day, rather than watching a live tape, is usually the more productive habit.
Quant workflows tend to need both, and this is where people get burned. Trailing drawdown rules in funded trading programs can be calculated intraday or at end of day, and those two methods produce very different risk profiles for the same equity curve. An intraday floor adjusts in real time and can flag a violation that an EOD calculation never would have caught. Backtest and evaluate a strategy on the same resolution it will actually trade on.
Run this checklist before deciding:
- Does your decision happen while the market is open, or after it closes?
- Do fills at the exact intraday price matter to your P&L, or just the daily range?
- Is the cost of a delayed reaction high enough to justify paying for speed?
Pro Tip: Before you pay for a real-time upgrade, pull a week of your own trade log and check how many entries would have changed if you’d acted 15 minutes later. If the answer is “none,” EOD data is probably doing you fine.
What Upgrading Your Data Plan Actually Buys You
Vendors rarely sell you speed and history separately. Most build a ladder: free EOD, a 15 minute delayed tier, and a paid real-time plan, and the paid tier often bundles a much deeper historical archive alongside the live stream.
- Free EOD plans typically cap history at a few years and update once daily.
- Delayed feeds sit in the middle, useful for casual monitoring but useless for execution.
- Real-time plans vary enormously in how many years of history and how many symbols they include.
That bundling means “upgrading for speed” sometimes actually buys you data depth you didn’t know you needed, and other times you’re paying real-time prices for history you could get elsewhere for free. Check both axes of any vendor’s plan before assuming the price gets you what you think it does, since some pricing ladders bundle these in ways that aren’t obvious from the marketing page. Delivery format matters too: EOD and historical data almost always ship over REST, a simple request and response. Real-time data streams over WebSocket connections that stay open and push updates, which means your infrastructure needs to handle reconnects and message ordering, not just parse a file.
Where Consolidated Market Data Actually Comes From
The prices you see on a retail platform usually trace back to the Securities Information Processors, the consolidated tape built under the CTA, CQ, and UTP plans that pool quotes and trades from every listing exchange into one public feed.
- The SIPs exist because no single exchange sees the whole market; consolidation is required by regulation.
- CT Plan governance has faced SEC scrutiny over conflicts between exchanges’ proprietary data businesses and their obligation to run the public consolidated feed fairly.
- Daily TAQ, built from that same consolidated data, becomes available the evening of the trading day and anchors the historical record back to 1993.
The SEC’s own MIDAS system notes that high-frequency firms and market makers rely on microsecond-level proprietary feeds, while most retail and institutional investors do their analysis just fine on consolidated data. That’s a useful reality check: unless you’re competing on microseconds, the public feed is enough.
Backtesting on EOD: What It Can and Can’t Tell You
EOD data backtests cleanly for strategies that hold positions across sessions, moving average crossovers, sector rotation, most value and momentum screens. It breaks down the moment your rules assume something that only exists intraday.
- Confirm your entry/exit rule doesn’t secretly assume an intraday stop or a VWAP fill; if it does, you need intraday bars, not daily rows.
- Check whether the fill price your backtest assumes actually appears in the EOD row, or if it’s an intraday level that never shows up in OHLC data.
- Match your dataset’s resolution to your rules before trusting the results — choosing a timeframe without fooling yourself is crucial for accurate backtests (Choosing a timeframe without fooling yourself). Mismatched resolution is one of the most common reasons backtests lie about real-world performance. For picking the right window in the first place, a solid rule of thumb on timeframe selection helps avoid overfitting to noise.
Combining Real-Time Streams With Historical Context
Most serious trading setups run two pipes at once: a streaming feed for execution and an EOD or historical database for context and reconciliation. A screener that flags unusual volume in real time still needs yesterday’s close to calculate that volume against something. Before wiring the two together, sync your clocks (streaming timestamps and EOD timestamps often use different conventions), reconcile daily totals against the official close, and respect API rate limits on both sides. Databricks frames this as standard practice: use streaming for low-latency decisions, batch data for trend analysis, and don’t force one system to do both jobs badly.
How MarketCapLens Fits Into a Real-Time and EOD Workflow
MarketCapLens tracks over 2,500 companies with market-cap and price data refreshed multiple times daily, giving you a fast way to confirm a daily close, check a sector snapshot, or pull a market-cap number before acting on a live signal.
Three Rules of Thumb for Choosing Your Data Tier
Decide by decision timing, not by what sounds more professional: if your P&L depends on sub-second fills, pay for streaming; otherwise put the budget toward deeper history. Sample your own trade log before upgrading. A week of real fills tells you more than any vendor’s pitch. And when a provider claims “real-time,” ask whether they mean zero deliberate delay or just a faster delay. Those are not the same promise.
— MarketCapLens
Check Daily Closes and Sector Context Before You Upgrade
Before you commit to a real-time subscription, it’s worth confirming whether you actually need it. A service offers a free way to check refreshed market-cap rankings and daily price snapshots across thousands of companies, updated multiple times a day, without paying for a streaming plan you might not use.
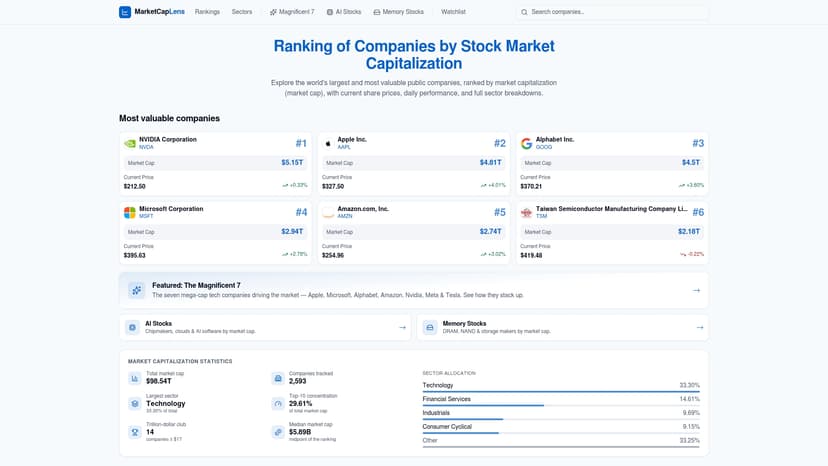
If your trading is closer to swing or position holding than scalping, that kind of daily context often covers what you need. Use it to confirm yesterday’s close, compare sector allocations, or check how a stock’s market cap has shifted before deciding whether real-time execution data is worth the added cost. If you’re still fuzzy on how market cap numbers actually work, the plain-English guide to market capitalization is a good five-minute read. Start by pulling up the market cap rankings and see how far daily-refreshed data actually gets you.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
FAQ
What’s Better, EOD or Intraday Data?
Neither is better outright; it depends on when your decisions happen. Intraday (real-time) data wins for anything executed during market hours, while EOD data wins on cost and is more than sufficient for backtesting most swing and position strategies.
What Are Examples of Real-Time Data?
Live bid/ask quotes, executed trade prints, and order-book depth (Level 2 data) are the core examples, all delivered with transport latency but no deliberate delay. Streaming APIs and exchange direct feeds are the typical delivery method.
Does a Brokerage App Show Real-Time Data?
It depends on the platform and account type; some brokerages provide real-time quotes by default while others show data delayed by 15 minutes unless you opt into a real-time data agreement. Check your specific platform’s data disclosures rather than assuming either way.
What Does Real-Time Data Mean?
Real-time data means information is delivered essentially as it happens, with only the unavoidable transport latency between the event and your screen. That’s distinct from delayed data, which intentionally withholds the feed for a set period, commonly 15 minutes.
Can I Use MarketCapLens Instead of a Real-Time Feed?
For execution-level trading, no. But for checking daily closes, market-cap shifts, and sector performance without paying for a streaming subscription, MarketCapLens’s multiple-times-daily refreshed data covers most research and monitoring needs.
Recommended
For informational purposes only and is not investment advice. Do not rely on the facts, figures, ticker symbols, or other statements in this article — they may be incomplete, outdated, or incorrect, and we are not responsible for errors. See our disclaimer.