3 Quick MarketCapLens Checks Analysts Use for Buybacks and Market Cap
By MarketCapLens · Published · 13 min read
Buybacks shrink the share count, which mechanically lifts earnings per share and per-share valuation metrics, but they do not automatically create intrinsic firm value. The first things to check are the dollar amount announced, the buyback yield (repurchases divided by market cap), and whether shares were actually retired. For quick verification, SEC filings and a market-cap tracker like MarketCapLens cover the two sides of the check.
TL;DR:
- Buyback yield and percent of market cap help evaluate buyback size relative to company size, with thresholds indicating more aggressive or conservative commitments.
- Funding source matters: cash-funded buybacks are less risky and less likely to distort enterprise value or increase leverage compared to debt-funded programs.
- Empirical evidence shows buybacks create only modest, often durable, share price increases and generally do not crowd out corporate investment.
- EPS gains from buybacks can be misleading, as they often result from increased risk rather than genuine operational improvement, especially if financed by debt.
- Sectoral shifts, like increased capital expenditures in AI, may signal disciplined investment, and buybacks outperform dividend payouts when executed below intrinsic value and funded with cash.
MarketcaplensTrack Market Cap Beyond BuybacksCompare market capitalization, share prices, sectors, historic data, and daily performance across more than 2,500 public companies.Visit MarketCapLens
Table of Contents
- How buybacks change share counts, EPS, and the market-cap math
- Measuring buyback magnitude: yield, percent of cap, and volume limits
- What the evidence says about price impact and crowding out capex
- Rule 10b-18, disclosure rules, and the excise tax
- A practical framework for judging whether buybacks create value
- Reproducing these metrics with MarketCapLens
- Reading the 2020s buyback wave correctly
- MarketCapLens: tools for tracking buybacks and market-cap effects
- FAQ
- Sources
How buybacks change share counts, EPS, and the market-cap math
Market capitalization is share price multiplied by shares outstanding. When a company retires shares through a buyback, it shrinks the denominator in every per-share calculation, including EPS, without necessarily touching the numerator that matters most: operating income. If net income stays flat and the share count drops, EPS rises by arithmetic alone. That is a real accounting effect, but it says nothing about whether the business got more valuable.
Enterprise value tells a different story. Enterprise value equals market cap plus debt minus cash, so a buyback funded from existing cash reserves shifts value from the balance sheet into the share price without changing enterprise value much at all. The picture changes when a company borrows to fund repurchases: debt rises, cash doesn’t build back up, and the capital structure becomes more leveraged even as market cap holds steady or climbs. That shift raises financial risk, which is part of why EPS gains from debt-funded buybacks deserve more skepticism than those funded from free cash flow. You can see the mechanics of this distinction laid out in our guide to market cap versus enterprise value.
Companies execute buybacks through three main channels, and each leaves a different trail for analysts to follow:
- Open-market repurchases: the company buys shares gradually on the exchange, typically spread across weeks or months, and must follow Rule 10b-18’s volume and timing conditions to stay inside the safe harbor.
- Tender offers: the company announces a fixed price and quantity, shareholders choose whether to sell, and the transaction completes in a tight window, producing a visible, immediate change in shares outstanding.
- Accelerated share repurchases: the company pays a bank upfront for a large block of stock, receives most of the shares immediately, and settles the final share count later based on a volume-weighted average price.
Each method shows up differently in filings. Open-market programs appear as ongoing authorizations with periodic execution updates, while tenders and accelerated repurchases tend to show large, one-time changes in share count. The authoritative source for execution detail is the issuer repurchase table required in Forms 10-Q and 10-K, which breaks down shares bought, average price paid, and shares remaining under existing authorizations.
Measuring buyback magnitude: yield, percent of cap, and volume limits
Raw dollar figures for buybacks mean little without context. A $5 billion repurchase program is a minor event for a company with an $800 billion market cap and a major one for a $20 billion company. Two ratios fix that problem.
Buyback yield divides trailing twelve-month repurchase dollars by current market capitalization. This ratio helps indicate the relative size of buybacks compared to company size for total shareholder return calculations. Percent of market cap for an announced authorization works the same way: divide the dollar size of the newly approved program by market cap at announcement to gauge how aggressive the commitment is relative to the company’s size.
Open-market repurchases are also bound by volume limits under Rule 10b-18’s safe harbor, which caps daily purchases at 25% of the stock’s average daily trading volume (ADTV), excluding certain block trades that qualify for separate treatment. ADTV is typically computed over the preceding four weeks, and staying under the cap protects the issuer from being treated as a market manipulator under the relevant anti-fraud provisions. A company announcing a buyback far larger than its ADTV can support within a reasonable timeframe is signaling either a long execution horizon or an intent to use tenders and accelerated structures instead of pure open-market buying.
To size and compare buybacks reliably, analysts need three inputs:
- Trailing twelve-month repurchase dollars, taken from the cash flow statement or the issuer repurchase table in the 10-K.
- Current market capitalization, pulled from a live data source rather than a stale filing date.
- Average daily trading volume over a recent four-week window, to check whether an announced program is executable within the safe harbor’s volume constraints.
With those three numbers, buyback yield, percent-of-cap sizing, and ADTV feasibility checks all become straightforward calculations rather than guesswork.
What the evidence says about price impact and crowding out capex
Large-sample academic work gives a more measured picture of buybacks than the headlines suggest. A large-sample study of share repurchases covering decades of data found that repurchases account for only a small fraction of total trading volume, that the price reaction following announcements tends to be modest rather than dramatic, and that those gains typically do not reverse in the following months. The same research found no systematic evidence that repurchase spending crowds out corporate investment, a conclusion that runs against a common criticism of buyback programs.
That modest, durable price effect matters for how analysts should calibrate expectations. A buyback announcement is often read by the market as a signal of management confidence in free cash flow generation rather than a guaranteed price lever, and the data support treating it that way: real but limited.
One finding that keeps getting restated in different forms is the EPS-accretion fallacy. A formal analysis published in the Financial Analysts Journal shows that EPS growth from a buyback can be mathematically real while representing a worse trade for shareholders, not a better one. Retiring cash, which carries low risk and a low expected return, shifts the remaining asset base toward riskier operating assets with higher expected returns. EPS rises because the company is now riskier, not because it generated more intrinsic value. An analyst who treats every EPS lift as a sign of operational improvement will misprice exactly the companies most reliant on buybacks to hit per-share targets.
Three caveats should temper any blanket conclusion:
- Selection bias: companies that repurchase stock tend to already be cash-generative and relatively healthy, so the group’s average performance is not a random sample of the market.
- Measurement windows: short post-announcement windows can overstate price effects that fade or stabilize over longer horizons.
- Sector and cycle differences: a capital-intensive sector in a heavy investment cycle behaves differently from a mature, cash-rich sector running steady repurchase programs.
Aggregate buyback spending has recently exceeded aggregate dividend payouts across the US market, with buybacks topping $1 trillion against roughly $740 billion in dividends for the trailing twelve months through September 2025. That gap is the practical reason total shareholder yield, not dividend yield alone, has become the more complete screening metric for cash return to shareholders.
Rule 10b-18, disclosure rules, and the excise tax
Repurchases executed on the open market fall under Rule 10b-18’s voluntary safe harbor, which protects issuers from manipulation claims when trades meet four conditions:
- Manner of purchase: trades generally go through a single broker or dealer per day.
- Timing: purchases avoid the opening of trading and the final minutes before the close, depending on the security’s trading characteristics.
- Price: the issuer cannot pay more than the highest independent bid or last transaction price, whichever is higher.
- Volume: daily purchases stay within 25% of ADTV, with a separate allowance for qualifying block purchases outside that daily cap.
On the disclosure side, issuers must report repurchase activity in tabular form in their 10-Q and 10-K filings, breaking out shares purchased each month, average price paid per share, and shares that remain available under existing authorizations. These tables are the most reliable way to confirm whether an announced program is actually being executed or sitting dormant, since authorization announcements and real purchasing activity frequently diverge.
A 1% excise tax on net stock buybacks, enacted as part of broader tax legislation, adds a modest cost to repurchase programs. A Congressional Research Service analysis walks through the tax’s structure and the debate over how much it actually changes corporate repurchase behavior, noting that the incremental cost is small relative to typical buyback yields and has not visibly suppressed aggregate buyback volume.
Pro Tip: When verifying a repurchase program, check the 10-Q or 10-K repurchase table for “total number of shares purchased,” “average price paid per share,” and “maximum number of shares that may yet be purchased.” Mismatches between the authorized amount and the shares actually bought are common and change the real buyback yield.
A practical framework for judging whether buybacks create value
Total shareholder yield, the sum of dividend yield and buyback yield, is the starting screen. It captures the full cash return to shareholders in a way dividend yield alone increasingly misses, given how large aggregate buyback spending has become relative to dividends.
From there, a repeatable due-diligence sequence separates disciplined capital allocation from financial engineering:
- Compare the buyback price to a conservative intrinsic valuation. Repurchases executed well below fair value transfer wealth to remaining shareholders; repurchases executed above fair value do the opposite.
- Identify the funding source. Cash-funded buybacks preserve the balance sheet; debt-funded buybacks raise leverage and financial risk even when the share price reaction looks identical.
- Check the trend in ROIC and capital expenditure. A company buying back stock while ROIC declines and capex shrinks may be substituting financial engineering for reinvestment.
- Look at executive incentive structures. Compensation plans tied heavily to EPS targets create an incentive to buy back stock regardless of valuation, since EPS accretion is partly mechanical.
- Confirm share retirement and disclosure transparency. Some programs offset share issuance from employee compensation rather than shrinking the float, which mutes or eliminates the per-share benefit analysts expect.
A few patterns should lower confidence in a given buyback program: repeated authorizations that never translate into retired shares, repurchases funded by new debt issuance in the same period, and buyback activity that accelerates precisely when ROIC is falling, which often signals an attempt to mask weakening fundamentals with per-share arithmetic.
Pro Tip: When modeling forward EPS, build a version of the forecast that assumes no further buybacks and compare it to the consensus estimate. The gap between the two numbers isolates how much of expected EPS growth is arithmetic rather than operational.
Separating the arithmetic lift from the operating story also helps when comparing free cash flow forecasts. If free cash flow per share is growing faster than free cash flow in aggregate, the gap is coming from the shrinking share count, not from the business generating more cash, and that distinction belongs in the valuation writeup, not buried in a footnote.
Reproducing these metrics with MarketCapLens
Running the calculations above only takes a handful of data points, and most of them live on a few pages. Start with the company’s current market cap rankings entry to get live share price and shares outstanding, then layer in historical shares outstanding to see how the float has moved over the trailing year or longer.
A short workflow looks like this:
- Pull current market cap from the company’s profile page to use as the denominator for buyback yield and percent-of-cap.
- Check historical shares outstanding across recent quarters to confirm whether the float actually shrank or merely held steady despite an announced program.
- Cross-reference sector pages, such as the technology sector rankings, to compare buyback intensity across peers of similar size.
- Verify against the SEC repurchase table in the company’s most recent 10-Q or 10-K to confirm the dollars actually spent match what the market-cap data implies.
For sector-specific examples, the AI stocks market-cap page is useful for spotting companies where heavy capital expenditure on infrastructure is competing with repurchase spending for the same cash flow, a dynamic that shows up clearly when comparing buyback yield against capex intensity side by side.
Pro Tip: *Use sector screens to benchmark a company’s buyback yield against close peers rather than the market average.
Reading the 2020s buyback wave correctly
Aggregate buyback spending has grown large enough to outpace dividends, but size alone doesn’t tell you which companies are using repurchases well. The honest takeaway from the evidence is unglamorous: buybacks move per-share numbers reliably and intrinsic value only sometimes, and the difference almost always comes down to price discipline and funding source rather than the headline dollar figure.
The more interesting shift to watch is sectoral. Heavy AI-related capital spending is drawing cash away from repurchases in parts of the technology sector, even as aggregate buyback dollars across the market hit records. A portfolio tilt toward disciplined repurchasers, companies buying below conservative fair value with cash rather than debt, holds up better across cycles than a blanket preference for any company with a large authorization on the books. Watch the capex-versus-buyback tradeoff closely over the next few years: it may turn out to be a better forward indicator of capital discipline than the buyback headline itself.
— MarketCapLens
MarketCapLens: tools for tracking buybacks and market-cap effects
Our market cap rankings update real-time share prices and historical shares outstanding across a large number of companies, with sector breakdowns that make it straightforward to compare buyback intensity across peers rather than in isolation.
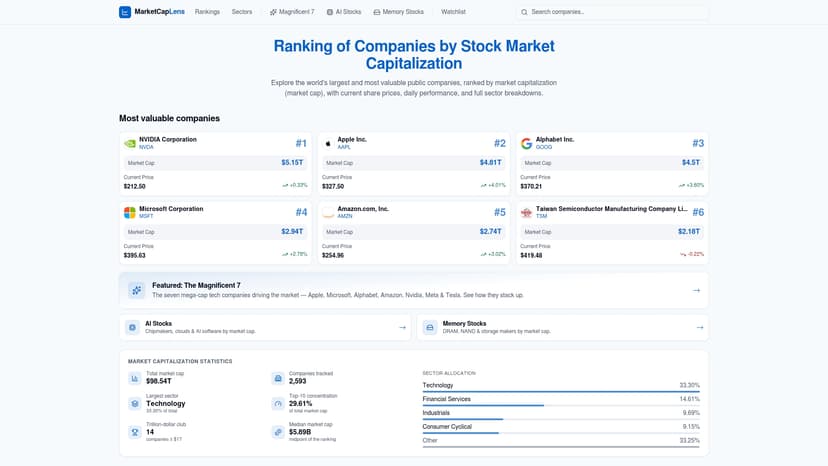
Two pages are the natural starting point for the workflow in this guide: our market cap rankings for live data on any company you’re tracking, and our explainer on what makes a company’s market cap go up or down for the broader context behind the share-count arithmetic covered above. If you want a forensic, filing-by-filing view of whether a specific company’s buyback narrative matches its actual execution, the capital allocation analysis from Lacuna Journal adds a useful second opinion alongside our market-cap data.
Open any company profile on a market cap ranking site, pull the trailing twelve-month repurchase figure against current market cap, and you have a buyback yield in under a minute, ready to compare against the sector benchmarks and red flags covered in this guide.
FAQ
Do buybacks reduce market cap?
Buybacks reduce shares outstanding, not market cap directly, since market cap is share price multiplied by share count and the price typically adjusts to reflect the cash leaving the business. A buyback funded from cash on hand tends to leave enterprise value roughly unchanged while shifting value from the balance sheet into the remaining shares, as explained in our market cap versus enterprise value guide.
What does Warren Buffett think about share buybacks?
Buffett has publicly favored buybacks executed at or below a conservative estimate of intrinsic value, arguing they benefit remaining shareholders in that case, while criticizing repurchases made simply to offset dilution or hit EPS targets regardless of price. The distinction tracks closely with the price-discipline check analysts should run before treating any buyback as value-creating.
How much is the stock buyback excise tax?
The federal excise tax on net stock buybacks is 1%, a rate established in US tax legislation and summarized in a Congressional Research Service report on its structure and effects. The tax adds a modest cost to repurchase programs but has not visibly reduced aggregate buyback volume.
Is Nvidia buying back its own stock?
Buyback activity and announced authorizations for any specific company, including Nvidia, change frequently and are best confirmed on the company’s own 10-Q or 10-K repurchase table or a live market-cap tracker rather than a static answer here. Checking the issuer repurchase table directly is the most reliable way to see whether shares were actually bought and retired in a given period.
Sources
- Stock Repurchases and the EPS Enhancement Fallacy: Financial Analysts Journal
- Share Repurchases on Trial: Large-Sample Evidence on Share Price Performance, Executive Compensation, and Corporate Investment (SSRN)
- Rule 10b-18 purchases of certain equity securities by the issuer and others | SEC
- Stock Buybacks Are Booming in 2025. That’s Bad News for Dividend Investors | Morningstar
Recommended
For informational purposes only and is not investment advice. Do not rely on the facts, figures, ticker symbols, or other statements in this article — they may be incomplete, outdated, or incorrect, and we are not responsible for errors. See our disclaimer.