S&P 500 Tech Sector Weight: Nearly 40%, Verify It Live
By MarketCapLens · Published · 11 min read
Information Technology now makes up roughly the high-30s to low-40s percent of the S&P 500, a share that has nearly doubled since the 2010s. For investors, that means index returns now hinge on a small group of mega-cap companies, and tracking that concentration matters as much as tracking the index itself. We built this breakdown using live sector data so you can verify every figure yourself.
TL;DR:
- The top 10 S&P 500 companies hold roughly 40 to 41% of index value, so check fund holdings rather than relying on sector labels.
- An equal weighted S&P 500 fund can reduce reliance on mega cap leaders, but it may lag when a small group continues to dominate.
- Nasdaq funds often overlap with S&P 500 mega cap holdings, while MSCI World adds geographic and sector breadth but still includes large US technology companies.
- Sector weights shift with prices and index changes, so check each figure’s date and calculation method before comparing snapshots from different providers.
MarketcaplensTrack Market Cap And Sector TrendsMarketCapLens brings together current share prices, sector breakdowns, historical data, and market trends to help you examine concentration.Explore MarketCapLens
Table of Contents
- Snapshot: current sector weight breakdown and top contributors
- Historical trend: how tech grew to its current share
- Concentration analysis: the role of the largest stocks and skew
- What concentration means for investors: diversification, risk, and returns
- How sector weight is measured and where to get accurate data
- MarketCapLens insight: live data check and practical interpretation
- Comparison of tech sector weight across different major stock indices
- Impact of tech sector weight fluctuations on overall market volatility and investor sentiment
- Historical context: how technological innovations influenced sector weight changes over decades
- Author perspective: what market watchers should watch next
- How MarketCapLens helps: tools and next steps
- FAQ
- Sources
Snapshot: current sector weight breakdown and top contributors
The Information Technology sector’s share of the S&P 500 sits in the high-30s to low-40s percent range, up from under 7% in 1990, according to long-term sector weight data. That growth has not come from hundreds of companies rising together. It comes from a handful of dominant firms, often grouped under the shorthand “Magnificent Seven,” that now account for a disproportionate slice of total index value.
A few things explain how so few names can carry so much weight:
- The index is market-cap weighted, so a company’s price move directly shifts its share of the whole.
- Mega-cap tech firms have grown earnings and valuations faster than most other sectors over the past decade.
- Cloud computing, semiconductors, and AI infrastructure spending have concentrated growth in companies already near the top of the index.
- When these firms report strong quarters, the index as a whole tends to move with them, not just the tech sector.
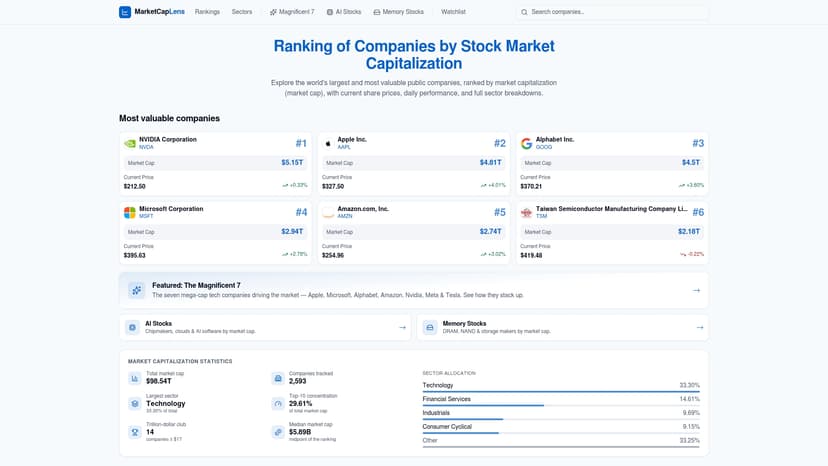
You can see this breakdown live on our technology sector page, which ranks the largest companies by market capitalization and updates throughout the trading day.
Historical trend: how tech grew to its current share
The tech sector’s weight moved in bursts, each tied to a distinct wave of business-model change, according to sector weight history.
- Late 1990s: the dot-com buildout pushed tech weight up sharply, then the 2000 crash pulled it back down just as fast.
- 2010s: the rise of mobile computing and cloud subscription models rebuilt tech’s share on steadier earnings rather than speculative valuations.
- Early 2020s: pandemic-era demand for digital services accelerated adoption curves that were already underway.
- 2023 to 2026: AI infrastructure spending, from chips to data centers to foundation models, became the dominant driver of incremental tech earnings and valuation growth.
A chart plotting tech’s sector weight against these inflection points would show two distinct peaks, the 2000 run-up and the current one, separated by nearly two decades of steadier, cloud-driven growth. The difference this time is that today’s weight rests on substantial reported earnings growth, not purely on multiple expansion, a distinction Deloitte’s analysis of tech investment ties to accelerated AI adoption since 2023.
Concentration analysis: the role of the largest stocks and skew
Sector weight tells you how much of the index one industry occupies. Concentration tells you how much of that weight sits inside just a few companies, and that second number matters more for risk. Analysts typically look at “top-N weight,” the combined share held by the five or ten largest constituents, as a plain-language stand-in for more technical concentration measures like the Herfindahl index.
The top 10 companies in the S&P 500 now account for roughly 40 to 41% of the index’s total value, according to MarketCapLens analysis of S&P 500 concentration, meaning the other 490-plus companies share the remaining majority unevenly. When concentration runs this high, the index’s performance can diverge sharply from the “average” stock’s performance.
A few practical effects follow from this:
- Index returns increasingly reflect a handful of earnings reports rather than broad economic health.
- Volatility in two or three mega-cap names can swing the entire index’s daily return.
- Diversification benefits from holding “500 stocks” shrink as effective breadth narrows.
Research from S&P Dow Jones Indices notes that historical cycles of rising concentration have tended to favor cap-weighted index performance, while periods of falling concentration have often favored equal-weighted approaches.
What concentration means for investors: diversification, risk, and returns
Cap-weighted indices like the S&P 500 automatically give more influence to companies as they grow larger. That structure rewarded investors handsomely while mega-cap tech outperformed, but it also means a downturn in those same names carries outsized weight. Equal-weighted index versions, which give every constituent roughly the same share regardless of size, perform differently across cycles: S&P Dow Jones Indices research shows equal-weighted approaches can outperform when market gains broaden beyond the largest names, and lag when a small group keeps dominating.
A few practical responses worth considering:
- Check your fund’s top-10 holdings concentration, not just its sector label, since many “diversified” funds are quietly tech-heavy.
- Consider an equal-weight S&P 500 fund as a complement if you want less reliance on mega-cap performance.
- Rebalance periodically rather than letting winners compound into an ever-larger share of your portfolio.
Pro Tip: Revisit your top-10 holding weights quarterly, since a single strong earnings season can quietly shift your portfolio’s concentration without you buying or selling anything.
How sector weight is measured and where to get accurate data
Sector weight is calculated by summing the float-adjusted market capitalization of every company in a sector and dividing it by the float-adjusted market capitalization of the full index. Float adjustment excludes shares not available for public trading, like those held by founders or governments, so the figure reflects tradeable value rather than total shares outstanding.
A few sourcing notes worth knowing before you quote a number:
- S&P Dow Jones Indices publishes the official index composition and sector weights that most data providers reference.
- Data providers track these weights alongside daily price and market-cap data across more than 2,500 companies, with updates multiple times a day.
- Figures can shift between index rebalancing dates, so a snapshot taken mid-quarter may differ slightly from the official quarterly reconstitution.
- Always check the “as of” date on any sector weight figure before comparing it to another source.
MarketCapLens insight: live data check and practical interpretation
You do not need to take any single source’s word for the current tech weight. Various platforms track real-time share prices and market capitalization across thousands of companies, with sector breakdowns that update multiple times throughout the trading day, so you can reproduce the top-contributor math yourself.
Here is a simple way to check it:
- Open our sectors page and sort by market capitalization within Information Technology.
- Sum the market caps of the top 5 or top 10 companies listed.
- Divide that sum by the total S&P 500 market capitalization to get your own top-N weight figure.
- Use the Market Cap Calculator if you want to verify any individual company’s price-times-shares figure before including it.
Pro Tip: Run this check monthly rather than once, since a single strong or weak earnings cycle among the largest names can move the top-10 share by a percentage point or more.
Comparison of tech sector weight across different major stock indices
Tech’s share of the index looks very different depending on which benchmark you check. The S&P 500’s Information Technology weight sits in the high-30s to low-40s percent range, but that figure understates tech’s real influence, since several companies classified under “Communication Services” or “Consumer Discretionary,” like large internet platforms, behave economically like tech firms despite their formal sector label.
The Nasdaq Composite and Nasdaq-100 run considerably more tech-heavy by construction, since both indices are built around technology and growth-oriented companies from the outset rather than spanning the full economy. MSCI World, which spreads exposure across developed markets outside the United States as well as within it, generally shows a lower technology weight than the S&P 500, reflecting the heavier presence of financials, industrials, and consumer sectors in non-US developed markets.
The practical takeaway: if you hold a Nasdaq-100 fund thinking it diversifies your S&P 500 tech exposure, it likely does the opposite, since both benchmarks draw from an overlapping set of mega-cap names. A global fund tracking MSCI World offers more genuine sector diversification away from technology, though it still carries meaningful tech exposure given how large US tech companies have become relative to the rest of the world. Comparing your actual fund holdings, not just the index name, remains the only reliable way to know your real technology exposure across a multi-fund portfolio.
Impact of tech sector weight fluctuations on overall market volatility and investor sentiment
When tech carries close to 40% of the index, its daily swings increasingly set the tone for the market as a whole. A steep drop in a handful of mega-cap names can pull the entire S&P 500 lower even when most other sectors post gains, simply because of how much index weight those names control. This dynamic has shown up repeatedly since 2023, as AI-related earnings reports or guidance changes from a small number of companies have moved the broader index on single trading days.
Investor sentiment has grown correspondingly more sensitive to tech-specific news: a semiconductor export restriction, a surprising AI capital-spending figure, or a disappointing cloud-revenue number can now shift broad market mood in a way that would have been unlikely when tech held a smaller, more proportionate share. Bain’s research on AI’s profit impact frames this as a structural shift, not a temporary one, estimating that AI puts $4.7 trillion of profits at stake across industries and will keep reshaping where capital and investor attention concentrate.
For anyone watching market volatility, the practical implication is that the “market” and the “tech sector” are no longer cleanly separable concepts. A volatility spike attributed to broad macroeconomic concern often traces back, on closer inspection, to price action in a small cluster of technology names. Separating genuine economy-wide risk from tech-specific risk has become a more useful exercise than it was a decade ago, and checking sector-level data rather than only the headline index number helps make that distinction.
Historical context: how technological innovations influenced sector weight changes over decades
Each major jump in tech’s sector weight traces back to a specific technological shift that changed how companies made money, not just investor enthusiasm. The personal computer and early internet buildout of the 1990s created the first wave of tech-heavy valuations, followed by the 2000 crash that proved valuations had outrun actual earnings.
The 2010s shift looked different: cloud computing and subscription software replaced one-time software sales with recurring revenue, giving tech companies more predictable earnings and justifying sustained higher valuations rather than speculative ones. Mobile computing expanded the addressable market for software and digital advertising simultaneously, adding another durable growth driver. Deloitte’s analysis of the current investment cycle finds that tech investment growth has outpaced total business investment since 2023, with productivity gains concentrated specifically in technology companies rather than spread evenly across the economy.
The AI wave since 2023 follows a similar pattern to cloud computing but moves faster: capital is flowing into chips, data centers, and foundation models at a pace that shows up in sector weight within quarters rather than years, illustrating how technology transforms trading education with AI. A working paper on AI’s macroeconomic effects through software engineering productivity estimates that AI-driven productivity gains materially affected firm valuations and economic output between 2022 and 2025, giving a concrete mechanism for why this wave has moved valuations and sector weight so quickly compared to prior technology cycles.
Author perspective: what market watchers should watch next
Watch three things: quarterly earnings concentration among the largest AI infrastructure spenders, any regulatory action on antitrust or AI specifically, and whether equal-weighted index performance starts closing the gap with cap-weighted returns. Weights can shift by a percentage point or more in a single volatile week. Verify any figure you read, including ours, against live data before acting on it.
— MarketCapLens
How MarketCapLens helps: tools and next steps
We built our sectors overview and Market Cap Calculator so you can check tech’s current weight and top-contributor shares yourself, anytime, rather than relying on a quarterly snapshot. Run a live check today to see where concentration stands right now.
FAQ
What are the current S&P 500 sector weightings?
Information Technology holds the largest single sector weight in the S&P 500, sitting in the high-30s to low-40s percent range as of mid-2026, according to sector weight data. You can check live, updated weightings across all eleven sectors on our sectors page.
Is the S&P 500 too tech heavy?
Whether tech’s weight is “too high” depends on your own diversification goals rather than a fixed threshold. What is measurable is that the top 10 companies now represent roughly 40 to 41% of the index’s total value, according to MarketCapLens concentration analysis, a level of concentration worth factoring into your own portfolio decisions.
What is a sector weight?
A sector weight is the percentage of an index’s total market value that one industry group represents, calculated by dividing that sector’s combined float-adjusted market capitalization by the index’s total float-adjusted market capitalization. It changes daily as stock prices move and periodically when index providers reclassify or add and remove constituents.
What are the sector weights of the S&P 500 for 2026?
As of mid-2026, Information Technology’s share of the S&P 500 sits in the high-30s to low-40s percent range, the largest of any sector, according to long-term sector weight tracking. You can view the current full sector breakdown, updated throughout the trading day, on our sectors overview.
How does the tech sector perform compared to other sectors?
Technology has outgrown most other S&P 500 sectors in both earnings and valuation over the past decade, driven in recent years by AI infrastructure spending, according to Deloitte’s analysis of the tech investment cycle. That outperformance is exactly why its index weight has grown so much relative to sectors like financials or industrials.
Sources
- What Past Sector Concentrations Tell Us About Today’s Tech-Heavy S&P 500
- Natural Selection: Tactics and Strategy with Equity Sectors
- AI-driven tech investment boom | Deloitte Insights
- AI puts $4.7 trillion of profits at stake, creating a competitive battleground across industries
- The Macroeconomic Effect of AI: Sizing the Software Engineering Channel
Recommended
For informational purposes only and is not investment advice. Do not rely on the facts, figures, ticker symbols, or other statements in this article — they may be incomplete, outdated, or incorrect, and we are not responsible for errors. See our disclaimer.