Size Factor Investing: Check SMB Before Buying Small Caps
By MarketCapLens · Published · 7 min read
The size factor is the historical tendency for smaller market-cap stocks to post higher average returns than large caps. It is not a reliable standalone premium: the evidence is concentrated in microcaps and sensitive to costs and timing. We recommend treating size as a quality-adjusted or multi-factor tilt rather than a blunt small-cap bet.
TL;DR:
- Academic SMB portfolios differ from small cap index funds because decile sorting, liquidity screens, float adjustments, and rebalancing rules change their holdings.
- The Fama and French library tracks SMB from July 1926, but returns cluster in the smallest deciles, vary by sample period, and show January seasonality.
- A modest tilt commonly occupies single digit to low double digit equity allocation, with quarterly or semiannual rebalancing to limit tracking error against broad benchmarks.
- Trading costs, bid and ask spreads, and market impact can erase apparent alpha in the smallest stocks, so backtests need realistic cost assumptions.
Marketcaplensmarketcaplens.comSee Companies by Market CapCompare market capitalizations, sector breakdowns, and historical data to examine how company size shapes the stocks you track.Explore market cap data
Table of Contents
- Defining and measuring size: market cap, SMB, and decile sorts
- Academic and historical evidence: Fama-French, long-run data, and critiques
- Implementing size exposure: vehicles, allocation, and execution risk
- Checking size exposure with everyday market-cap tools
- A practitioner’s honest read on the size factor
- Tools to test your own size exposure before you commit capital
- FAQ
- Sources
Defining and measuring size: market cap, SMB, and decile sorts
Market capitalization is simply shares outstanding multiplied by share price, and it is the standard metric FINRA uses to sort companies into small, mid, and large buckets. Academic research builds on this by forming SMB, short for “small minus big,” a long and short portfolio that isolates the return difference between small and large stocks after controlling for other variables.
The construction matters as much as the concept:
- Academic sorts typically rank all stocks into deciles or quintiles by market cap, then rebalance periodically.
- Index providers often apply additional screens such as liquidity minimums and buffer zones to reduce turnover.
- Rolling SMB series reflect a long/short spread, not a simple small-cap index return.
- Rebalancing frequency and float adjustments can shift which companies land in the small-cap bucket from one period to the next.
These differences explain why a small-cap index fund and the academic SMB factor can behave quite differently even though both are labeled “size.”
Academic and historical evidence: Fama-French, long-run data, and critiques
Fama and French (1992) showed that size and book-to-market together explain cross-sectional average returns better than market beta alone, a finding that became the foundation for SMB as a standard factor. The Fama-French data library has tracked SMB and related series since July 1926, giving researchers nearly a century of history to test the premium’s persistence.
The size premium’s history is long, but its reliability is not uniform: Fama-French data show returns heavily concentrated in the smallest deciles, with notable seasonality clustered around January and meaningful sensitivity to the sample period chosen.
More recent work complicates the simple story. Research on quality-adjusted size, including the Jacobs Levy / Wharton study, finds that controlling for firm “junk,” meaning low profitability and weak quality characteristics, makes the size premium larger, more stable, and less concentrated in extreme microcaps.
- Raw size exposure is noisy and dominated by a small subset of tiny, often illiquid stocks.
- Quality filtering converts that noise into a more investable tilt.
- The practical takeaway is that size alone is fragile, but size paired with discipline on quality holds up better across periods.
Implementing size exposure: vehicles, allocation, and execution risk
Investors have several ways to capture size exposure, each with a different risk and cost profile.
- Small-cap index ETFs offer broad, low-cost exposure but inherit the raw premium’s concentration in microcaps.
- Size-tilt mutual funds apply modest overweights to smaller names within a broader portfolio rather than a pure small-cap sleeve.
- Multi-factor funds combine size with value, quality, or momentum, which tends to dampen the premium’s fragility.
- Custom factor portfolios let sophisticated investors apply their own quality screens before weighting by size, echoing the Jacobs Levy approach directly.
Most practitioners now prefer quality-adjusted size or a blended size-plus-value-plus-quality sleeve over a standalone small-cap bet, since the blended approach reduces dependence on the thinnest, most illiquid names. A typical tilt runs in the single digits to low double digits of total equity allocation, sized to keep tracking error against a broad benchmark manageable, with rebalancing on a quarterly or semiannual cadence rather than constant adjustment.
Execution frictions deserve direct attention. The AQR white paper on the size effect documents that trading costs, bid-ask spreads, and market impact can erode or eliminate the modest alphas found in the smallest deciles. Before evaluating a size strategy’s allocation fit, it helps to review practical allocation bands for small versus mid cap exposure, which frame how much of a tilt makes sense relative to a core portfolio.
Pro Tip: Size any small-cap sleeve as if half its paper gains will be given back to transaction costs, then decide if the remaining exposure still earns its place.
Checking size exposure with everyday market-cap tools
Rather than waiting for a backtest to confirm a decile is overweighted, we find it faster to check composition directly against live rankings. Our market cap rankings let you see which companies currently sit in a given size bucket, while the calculators for size, value, and returns help size a position before you add it. Pairing a quick decile check with a glance at sector breakdowns by market cap also flags unintended sector concentration, a common side effect of small-cap tilts that quality filters alone do not catch.
A practitioner’s honest read on the size factor
Size is a real, long-documented pattern, not a myth, but treating it as a clean, standalone premium overstates what the data supports. The rule of thumb we would give any practitioner: size works best as an ingredient, filtered for quality and blended with value or profitability, never eaten raw as a microcap basket. Use it when you can tolerate the tracking error and have confirmed the underlying names clear a liquidity bar; avoid it when the only rationale is “small has historically beaten large,” because that rationale ignores exactly the concentration and cost problems the research keeps surfacing. Treat size the way a careful analyst treats any single factor: useful evidence, not a complete strategy on its own.
— MarketCapLens
Tools to test your own size exposure before you commit capital
Checking a size tilt against live data takes minutes, not a research project. Our market cap calculator lets you verify where a stock actually sits in the size spectrum before you assume it belongs in a small-cap sleeve, and our broader rankings by market capitalization make it easy to spot drift in decile composition between rebalances.
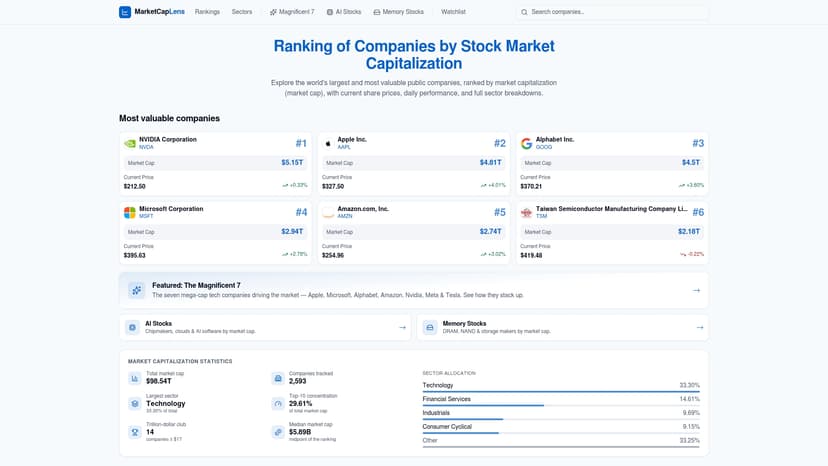
If you are building or monitoring a size tilt, start with a quick decile composition check using our market cap rankings to confirm the names you hold still qualify as the size exposure you intended.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
Is the size factor a reliable source of returns?
The size premium has a long history in the Fama-French data, but it is concentrated in the smallest, least liquid deciles and varies across sample periods. Research on quality-adjusted size, including the Jacobs Levy study, finds the premium becomes more stable once low-quality firms are filtered out.
How do I combine size with quality or value factors?
A common approach ranks stocks by size first, then excludes or downweights the lowest-quality quintile based on profitability before forming the final tilt. This quality-adjusted method, documented in the Jacobs Levy / Wharton research, produces a steadier premium than a raw size sort.
Do transaction costs really erode the size premium?
Yes. The AQR white paper documents that bid-ask spreads and market impact are large enough in the smallest stocks to eliminate much of the apparent alpha, which is why realistic cost assumptions belong in any backtest.
What data should I use to study the size factor myself?
Start with the Fama-French data library for long-run SMB series going back to 1926, and cross-check current size classifications against how market cap is defined and used. This pairing gives you both historical context and a current, practical check on classification.
How large should a size tilt be in a portfolio?
There is no universal number, and the right size depends on your tolerance for tracking error and your conviction in the underlying quality screen. Reviewing allocation guidance for small versus mid-cap exposure is a useful starting point before settling on a specific weight.
Sources
Before committing capital, run a regression of portfolio returns against SMB to estimate rolling factor betas and alphas, and check whether the exposure is stable across time rather than driven by one or two periods. Decile-level return patterns, liquidity profiles, and seasonal clustering around January are worth checking separately, since an average premium can mask lopsided contribution from a handful of tiny names.
- Kenneth R. French - Data Library
- The Cross-Section of Expected Stock Returns (Fama & French, 1992)
- Fact, Fiction, and the Size Effect (AQR white paper)
- Size matters if you control your junk (Jacobs Levy / Wharton study)
A useful complementary step before sizing positions is reviewing filing-based quality checks, since the kind of red-flag and disclosure review covered in FilingsIQ’s guide to evaluating stock before investing overlaps directly with the quality screens that make size exposure more durable.
Recommended
For informational purposes only and is not investment advice. Do not rely on the facts, figures, ticker symbols, or other statements in this article — they may be incomplete, outdated, or incorrect, and we are not responsible for errors. See our disclaimer.