S&P 500 Top 10 Concentration: Has It Passed 40% Again?
By MarketCapLens · Published · 8 min read
The S&P 500’s largest ten companies have at times made up more than 40% of the index by market capitalization, a level above the dot-com peak. For investors, that means index results now hinge on a handful of names, and a portfolio that looks diversified across 500 stocks can behave like a bet on one theme.
TL;DR:
- Past concentration extremes, including the dot com era, eventually eased as market leadership broadened, but history offers no reliable timetable for that shift.
- Top companies post stronger margins and returns on capital, but shared exposure to artificial intelligence, cloud, and advertising leaves them vulnerable to common shocks.
- Cap weighted indexes benefit more during narrow rallies, while equal weighted indexes reduce dependence on leaders but may lag and diverge from benchmarks for years.
- Audit your benchmark and overlapping funds, set review thresholds before markets move, and check monthly for long term holdings or weekly for tactical allocations.
Marketcaplensmarketcaplens.comTrack the Market’s Largest CompaniesCompare market-cap rankings, sector breakdowns, and historical data to examine how leadership and concentration change over time.Explore market cap rankings
Table of Contents
- 1. What does the current top 10 concentration snapshot show?
- 2. How did concentration evolve since 1990?
- 3. What is driving the top 10 higher?
- 4. How do cap-weighted and equal-weighted indexes compare?
- 5. How should you respond as an investor?
- 6. How can you verify concentration yourself?
- 7. Our perspective: monitor methodically, don’t panic
- 8. Which of our tools help you run a live check?
- FAQ
- Sources
1. What does the current top 10 concentration snapshot show?
The headline number comes from institutional research: at times the top 10 companies have constituted more than 40% of the S&P 500 by market capitalization, surpassing earlier peaks. We do not quote a single day’s reading here because the figure moves with every trading session; you can pull the live ranking on our Market Cap Rankings page and recompute it yourself.
The top 10 have at times exceeded 40% of S&P 500 market cap, surpassing earlier peaks, according to Commonfund. That is the anchor for everything below.
- The weights are float-adjusted, so a company’s index weight can differ from its raw market cap.
- The largest single constituent carries a weight that alone rivals entire sectors, and the remaining nine stacks on top of it.
- S&P Dow Jones Indices publishes an index built from exactly these ten names, and its sector breakdown shows information technology dominating.
Recent moves in the figure have tracked rallies in AI-linked megacaps. When those names outrun the other 490 stocks, the top 10 share climbs without any change in index membership.
2. How did concentration evolve since 1990?
The long view matters because it tells you whether today’s level is routine or extreme.
- Dot-com peak: technology and telecom leaders pushed the top weights sharply higher before the bust.
- Mid-2010s onward: concentration rose steadily as platform and cloud companies compounded earnings.
- Recent years: acceleration tied to AI enthusiasm took the top 10 past earlier records.
SPDJI research shows concentration rose sharply over the past decade, reaching extremes not seen for more than half a century. That framing is useful: today is unusual, but it is not unprecedented in kind.
The pattern across eras is also instructive. J.P. Morgan research describes extreme concentration as typically cyclical, echoing the Nifty Fifty and dot-com periods, with leadership historically broadening again over time. Reversion has not followed a fixed schedule, so treat it as a tendency, not a timetable.
3. What is driving the top 10 higher?
Three forces explain most of the move, and they differ in how durable they are.
- Earnings and margin concentration: Guinness Global Investors notes the current top 10 show stronger margins and returns on capital than the rest of the index. Part of the weight is earned.
- Thematic overlap: many leaders share the same growth driver, AI, plus cloud and advertising exposure. Guinness flags that shared driver as a source of fragility, because 500 names stop diversifying when the biggest ones respond to the same news.
- Flow feedback: inflows into cap-weighted funds force purchases of the largest names, which lifts their weights and invites more inflows.
The first driver is structural, the second can reverse quickly, and the third works in both directions.
Pro Tip: Check how much of the top 10 sits in the same sector before counting them as ten independent bets. Our tech sector weight analysis shows how heavy the tilt is.
4. How do cap-weighted and equal-weighted indexes compare?
Cap weighting automatically holds more of whatever has risen. When the largest names rally, a cap-weighted index benefits more than an equal-weighted one, which gives every company the same share and trims winners at each rebalance. When leadership broadens, the equal-weight approach tends to catch up.
S&P Dow Jones Indices research finds that higher top 10 concentration raises active risk and links concentrated leader rallies to cap-weighted outperformance, while equal-weight has tended to outperform after concentration retreats.
- Active risk: the more weight in ten names, the more a single stock’s move drives total portfolio volatility.
- Single-stock sensitivity: one earnings miss at a top holding now moves the whole index measurably.
- Tracking error: an equal-weight allocation held against a cap-weighted benchmark can diverge widely, in either direction, for years at a time.
- Sector exposure: a Northern Trust report shows equal-weighting reduces exposure to information technology and communication services, which dominate top 10 weights.
The tradeoff is real in both directions. Cap weighting rewards you while leaders keep winning and punishes you hardest when momentum stalls. Equal weighting lowers that dependence but gives up some upside during narrow rallies and carries its own small-cap and rebalancing tilt.
5. How should you respond as an investor?
Turn the analysis into a routine you can repeat.
- Run a concentration check. Sum the top 10 weights in your benchmark and in your own holdings, including funds that overlap.
- Set thresholds. Decide in advance what level of top 10 concentration would prompt you to review your portfolio. These are personal guidelines, not rules.
- Consider tilts. Weigh an equal-weight sleeve or an active tilt against your benchmark risk budget.
- Rebalance on a schedule. Regular reviews, plus an extra look after a sharp move in the leaders, can help keep drift in check.
Practitioners commonly shift part of an allocation toward equal weighting to harvest diversification return by selling winners and buying laggards. Other techniques include single-position limits, sector caps and opportunistic rebalancing when a leader’s weight jumps.
Match monitoring to your horizon. A long-term holder may check monthly, while a tactical allocator may want a weekly look. Our five-step portfolio audit walks through the process with live data.
Pro Tip: Write your trigger levels down before the market moves. Thresholds set in advance keep a rally from talking you out of a review.
6. How can you verify concentration yourself?
You do not have to take any published figure on faith. A short method reproduces it.
- Pull float-adjusted market caps for the index constituents on a single date.
- Sort descending and sum the top 10.
- Divide by the total float-adjusted market cap of the full index universe.
- Record the date, because the share shifts daily and a stale close will mislead you.
The fields that matter are float-adjusted market cap, the date of the series and sector tags. The common pitfalls are using unadjusted market caps, mixing dates across companies, and ignoring that several share classes can belong to one issuer.
Our rankings and historical views let you rebuild the list, and our guide to live concentration checks explains how to read the result. For deeper backtests, intraday S&P 500 history can help quants rebuild concentration series at finer resolution.
7. Our perspective: monitor methodically, don’t panic
We read the data as a call for routine, not alarm. Concentration at this level raises real risks, yet the same leaders have the margins and returns that justify part of their weight, and past extremes eased through gradual broadening. A measured stance means knowing your own top 10 exposure, deciding your tolerance in advance and reviewing it on a schedule. We built our rankings and historical views to help with that: our live concentration coverage offers more information. Run a check on your own portfolio this week and see how much of it rides on ten companies.
— MarketCapLens
8. Which of our tools help you run a live check?
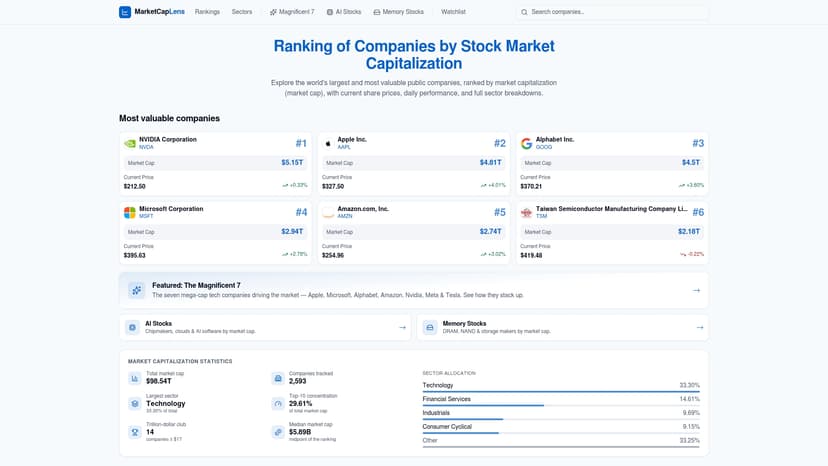
We built a few pages to help you audit your own holdings without a spreadsheet marathon. Pairing the live list with a quick calculation turns a headline percentage into a number you trust.
- Our Market Cap Rankings page lists the largest companies live, so you can sum the top 10 on any day.
- Our Market Cap Calculator multiplies price by shares to check any single company’s weight.
- Our tools hub gathers the other calculators for size, value and returns.
A good next step is the five-step audit, followed by a live check of your largest fund. Start on our rankings page and see where you stand today.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What is the concentration of the top 10 stocks in the S&P 500?
The top 10 companies have at times exceeded 40% of the index by market capitalization, according to Commonfund. The exact share changes daily with prices, so check a live ranking for today’s value.
What are the top 10 market caps?
The list is led by large US technology and platform companies, and the order shifts as prices move. You can see the current ranking on our Market Cap Rankings page.
Is market concentration good or bad?
It is a tradeoff. Concentration rewards cap-weighted investors while leaders keep rallying, but S&P research links it to higher active risk and greater sensitivity to single stocks.
What are the top 10 stocks by percentage of the S&P 500?
Each holding’s weight is its float-adjusted market cap divided by the index total, so the largest names carry the most. The S&P 500 Top 10 Index documents how these ten companies are weighted.
Sources
- Is Stock Market Concentration Rising? | J.P. Morgan Research
- Is there a rising concentration risk in the S&P 500? | Guinness Global Investors
Recommended
For informational purposes only and is not investment advice. Do not rely on the facts, figures, ticker symbols, or other statements in this article — they may be incomplete, outdated, or incorrect, and we are not responsible for errors. See our disclaimer.