Daily Market Performance: 2,500+ Company Data to Spot Narrow Rallies
By MarketCapLens · Published · 16 min read
The S&P 500 and Nasdaq closed at record highs while the Dow lagged slightly behind, a move driven less by broad enthusiasm than by a narrowing focus on upcoming corporate earnings. The S&P 500 gained 0.58% and the Nasdaq rose 0.45%, both fresh closing highs, while the Dow added a more modest 0.49%.
TL;DR:
- NYSE advancers outnumbered decliners 1.93 to 1, while Nasdaq breadth was nearly even at 1.01 to 1, pointing to concentrated index leadership.
- Volume was 16.50 billion shares, below the 20 day average of 17.51 billion; momentum traders should wait for above average activity before trusting follow through.
- Watch the 10 year Treasury yield and upcoming earnings guidance, because both can shift growth stock valuations after markets have priced in optimism.
- Traders should treat one session of weak breadth or light volume as a watch signal, not a trade trigger; wait for three consecutive confirming sessions.
- Long term investors generally should not rebalance after one session; wait for a sustained shift across breadth, volume, and sector rotation that changes target allocations.
MarketcaplensSee Beyond the Index HeadlinesExplore company-level market data, sector breakdowns, and historical trends to put daily performance in a broader context.Explore market data
Table of Contents
- What the day’s index numbers and breadth metrics show
- Yields, commodities, and earnings: the indicators driving today’s moves
- Were today’s gains broad-based or concentrated in a few sectors?
- How MarketCapLens turns index headlines into company-level insight
- A practical checklist for traders and long-term investors
- How does today’s move compare with typical daily patterns?
- Overnight futures and global markets set the early tone
- What sentiment indicators like the VIX reveal about the mood
- Notable stock movers that shaped the session
- Economic data releases that moved the market
- Reading today’s close against the broader market mood
- Turn today’s close into a clearer company-level view
- FAQ
- Sources
What the day’s index numbers and breadth metrics show
Index closes only tell part of the story. The real read comes from pairing the headline percent change with how many stocks actually participated in the move, how trading volume compared with recent norms, and whether new highs outpaced new lows.
On the session referenced above, the numbers broke down this way:
- The Dow Jones Industrial Average rose 253.14 points, or 0.49%, to 51,521.04.
- The S&P 500 added 45 points, or 0.58%, closing at 7,818.95, a record.
- The Nasdaq Composite climbed 122.48 points, or 0.45%, to 27,599.79, also a record close.
- Advancing issues outnumbered decliners by a 1.93-to-1 ratio on the NYSE, a sign of fairly broad participation in that segment of the market.
The session’s trading volume came in at 16.50 billion shares on US exchanges, below the 20-day average of 17.51 billion. Lighter-than-average volume on a record-high day is worth noting: it suggests the rally, while real, was not accompanied by the kind of heavy conviction buying that typically confirms a strong breakout.
Breadth told a more nuanced story depending on which exchange you looked at. The 1.93-to-1 advancer-to-decliner ratio on the NYSE pointed to wide participation, but the picture on the Nasdaq was different. There, advancers and decliners were roughly even, near a 1.01-to-1 ratio, even as the index itself notched a record close. That divergence between a flat advance-decline line and a record index level is a classic sign that a handful of large, heavily weighted stocks did most of the lifting.
New highs and new lows added another layer. Reports from the same session noted that the Nasdaq recorded a notable number of new highs and new lows simultaneously, a pattern that shows up when a market is bifurcated: certain pockets, often growth and technology names, pushing to fresh records while other segments quietly slide toward 52-week lows. That kind of split is easy to miss if you only glance at the index-level percent change.
For a quick daily gut check, three numbers matter more than the headline close:
- Breadth ratio: are advancers meaningfully outnumbering decliners, or is the index being carried by a few names?
- Volume versus average: is trading activity confirming the move, or is it quieter than normal?
- New highs versus new lows: is strength broad across the market, or concentrated in specific pockets?
Put together, the session described here was a genuine record close for two of the three major benchmarks, but one built on uneven participation and below-average volume rather than a uniformly strong advance. That distinction shapes how much weight a trader or investor should put on the headline number alone.
Yields, commodities, and earnings: the indicators driving today’s moves
Daily index moves rarely happen in isolation. Treasury yields, commodity prices, and the earnings calendar typically explain far more about why a session moved the way it did than any single headline number.
Treasury yields are commonly treated as a primary barometer for equity performance, since rising yields tend to pressure growth and technology valuations while falling yields often support them. When yields hold steady or drift lower, it tends to take pressure off the high-multiple names that dominate index weightings, which helps explain sessions where the Nasdaq and S&P 500 outpace the more value-tilted Dow.
Crude oil and broader commodity moves matter for a different reason: they ripple into energy sector earnings, transportation costs, and inflation expectations, all of which feed back into the same yield picture. A quiet day for commodities usually means one less variable for traders to price into rate expectations.
Earnings season acts as its own gravitational pull. Once major indices hit record territory, investor attention tends to pivot quickly toward upcoming earnings reports and corporate guidance, since a fresh high raises the bar for what “good news” looks like going forward. Analysts and investors alike tend to scrutinize forward guidance more closely after a record close, since the market has already priced in a fair amount of optimism.
A practical way to connect these dots on any given day:
- Check the 10-year Treasury yield direction first, since it tends to set the tone for growth versus value rotation.
- Scan whether crude oil or major commodities moved sharply, which can signal inflation or demand shifts.
- Note which companies reported earnings or guidance that session, since a single large report can move an entire sector.
Pro Tip: Before reacting to a single day’s move, check whether Treasury yields moved in the same direction as growth stocks. If they diverged, the equity move likely has a different driver, such as earnings or sector-specific news.
Were today’s gains broad-based or concentrated in a few sectors?
Index-level gains can mask a lot of internal disagreement about where the real strength lies. On the session covered here, large-cap technology and growth names appeared to do much of the heavy lifting behind the S&P 500 and Nasdaq records, while other corners of the market, particularly small caps, showed signs of lagging behind the headline strength.
That kind of divergence is not unusual during AI-driven rallies, where chipmakers and a small group of mega-cap platforms account for an outsized share of index-level gains. Large-cap concentration can mask underlying weakness, and checking market-cap-weighted concentration metrics is one of the more reliable ways to tell whether a “strong” day is actually broad or narrow.
A few patterns to watch when judging sector participation:
- Leaders tend to cluster: on days when growth stocks dominate, technology and communication services sectors often show the clearest gains.
- Laggards often show up in defensives or small caps: utilities, smaller industrials, or small-cap indices can lag even on a record day for large-cap benchmarks.
- Breadth divergence between exchanges is a tell: the NYSE’s 1.93-to-1 advance-decline ratio against the Nasdaq’s near-even split on the same session is a textbook example of large-cap strength outpacing broader participation.
The implication for sustainability matters here. A rally driven by a narrow band of mega-cap names can continue for a while, since those companies carry enormous index weight, but it tends to be more fragile than a rally where gains are spread across advancers, sectors, and market-cap tiers. When new highs and new lows appear side by side on the same exchange, as they did on the Nasdaq that session, it is a sign the market is bifurcated rather than uniformly strong.
Readers who want to check whether a similar pattern is forming on any given day can look at mega-cap thresholds and their outsized index influence or dig into how small- and mid-cap allocation tends to behave differently from large-cap benchmarks during concentrated rallies. The core takeaway is simple: a record close is a headline, but breadth and sector dispersion tell you whether that headline has real support underneath it.
How MarketCapLens turns index headlines into company-level insight
A headline index move only tells you that something happened. Figuring out what and where requires drilling from the index level down to the sector and company level, and that is where a broader data set earns its keep.
Our platform provides market-cap and price data for a broad range of publicly listed companies, refreshed multiple times a day to capture intraday shifts that help explain market breadth and sector performance.
Here is a simple way to move from macro headline to micro driver using our tools:
- Start with the rankings page to see which companies by market capitalization moved the most that day, since the largest movers by dollar value often explain a disproportionate share of an index’s point change.
- Check the relevant sector page to see whether the day’s strength or weakness was sector-wide or limited to one or two large names, which helps separate a genuine sector trend from a single-stock story.
- Run the numbers through our market cap calculator when a specific company’s move looks unusual, to see how its size and weighting compare with peers.
- Cross-check concentration using our analysis of S&P 500 concentration trends, especially on sessions where a handful of mega-cap names appear to be driving most of the index gain.
Pro Tip: When a sector page shows one or two companies moving sharply while the rest of the sector is flat, treat that as a single-stock story, not a sector trend, before adjusting any broader view of the market.
This kind of layered check, index first, then sector, then company, takes a few minutes and turns a vague headline into a specific, checkable explanation.
A practical checklist for traders and long-term investors
Reacting to a single day’s close without context is how both short-term traders and long-term investors end up making decisions they regret. A short checklist helps separate signal from noise.
- Check breadth first: look at the advance-decline ratio before reacting to the headline percent change, since a record close with weak breadth is a different situation than one with broad participation.
- Compare volume to the recent average: a move on below-average volume deserves less conviction than the same move on above-average volume.
- Identify the dominant driver: note whether yields, a commodity move, or an earnings report explains most of the session’s action.
- Review the top contributors: check which handful of large-cap names accounted for most of the index’s point change.
Suggested actions differ sharply by time horizon. A day trader or swing trader watching for momentum should pay closest attention to volume confirmation and breadth, since a narrow, light-volume rally is more prone to quick reversals. A long-term investor with a multi-year horizon generally has less reason to act on a single session at all, since one day’s breadth divergence rarely changes a thesis built on years of earnings growth.
A single day’s move, even a record close, should rarely trigger portfolio rebalancing on its own. Rebalancing makes more sense when a sustained trend, confirmed by breadth, volume, and multiple sessions of sector rotation, shifts your actual allocation meaningfully away from target weights. A one-day spike in a mega-cap name, by contrast, is rarely a good reason to sell a core long-term holding.
Pro Tip: Keep a simple rule: one day of narrow breadth or light volume is a note to watch, not a signal to trade. Three or more consecutive sessions confirming the same pattern is when it becomes worth acting on.
How does today’s move compare with typical daily patterns?
A 0.5% move in either direction is unremarkable by historical standards. Most trading sessions fall within a fairly narrow daily range, and the kind of divergence seen between NYSE and Nasdaq breadth on the same day is also a recurring pattern rather than an anomaly, particularly during periods when a small group of mega-cap growth stocks dominates index weighting.
What makes a session stand out is not the size of the index move but the combination of signals around it. A record close paired with below-average volume and flat breadth on one exchange is a pattern that shows up periodically during concentrated, earnings-driven rallies, rather than during broad, economy-wide expansions. Historically, these narrow-breadth record days tend to be followed by continued gains in the leading mega-cap names, but they are also more prone to sharp pullbacks if one of those leaders disappoints on earnings.
Comparing a given day against its own recent volume and breadth averages, rather than against some fixed historical benchmark, tends to be the more useful exercise. A 17.51 billion share 20-day average volume is itself a moving marker, and tracking how today’s volume sits against that rolling average gives a clearer sense of whether a move is typical or unusual than any single historical comparison point would.
Overnight futures and global markets set the early tone
By the time US markets open, overnight futures activity and overseas trading sessions have usually already shaped the day’s early direction, often influenced by historical intraday index data that traders analyze to gauge trends. Futures on the Dow, S&P 500, and Nasdaq trade through the evening and overnight hours, reacting to news out of Asian and European markets, corporate announcements, and shifts in bond yields that happen outside regular US trading hours.
A strong overnight session in Asian technology stocks, for instance, can set a positive tone for US futures ahead of the opening bell, particularly when the same chipmakers and AI-linked names that are driving US index gains also have exposure in those markets. European trading, which overlaps with the first few hours of the US morning, can add to or reverse that early tone depending on economic data releases or central bank commentary out of the region.
None of this guarantees the direction holds through the full session. Futures and overnight moves set an early bias, but domestic data releases, earnings reports, and Treasury yield moves during the regular session frequently take over as the larger drivers by midday. Treating overnight futures as a rough opening indicator, rather than a forecast for the full day, is the more realistic way to use them.
What sentiment indicators like the VIX reveal about the mood
Index levels tell you what happened to prices. Sentiment indicators like the CBOE Volatility Index, commonly called the VIX, and the put-call ratio try to capture how nervous or complacent options traders are about near-term moves.
A low VIX reading generally reflects a market that expects calm conditions ahead, which often coincides with steady, low-volatility grinds higher like the kind that can accompany record index closes. A rising VIX, even on a day when indices are up, can be a warning sign that options traders are paying up for downside protection despite the headline gain, a pattern sometimes seen when a rally is narrow rather than broad.
The put-call ratio works similarly: a ratio skewed heavily toward puts suggests traders are hedging more than usual, while a ratio skewed toward calls suggests more speculative optimism. Neither indicator should be read in isolation. A low VIX alongside weak breadth, for example, can suggest complacency rather than genuine strength, reinforcing the importance of checking sentiment readings alongside the breadth and volume metrics covered earlier rather than as a standalone signal.
Notable stock movers that shaped the session
Individual stock catalysts often explain a disproportionate share of an index’s point change on any given day, especially when a mega-cap name beats or misses earnings expectations or issues updated guidance. A single large technology or chipmaker name raising its revenue outlook, for example, can move not just its own share price but the sector page and index weighting tied to it.
Earnings season specifically tends to generate concentrated stock-specific moves: a company raising full-year guidance can see an outsized single-day jump that ripples into the index given its market-cap weighting, while a disappointing guidance update can do the opposite even on a day when the broader index is higher. That is part of why analyst and investor attention tends to pivot toward earnings calendars once a major index hits a fresh record, since the next catalyst for continuation or reversal is often sitting in an upcoming earnings report.
Readers tracking which companies are driving a specific sector’s move can check sector-level pages for technology sector rankings to see which names are leading or lagging within a given group, rather than relying on index-level headlines alone.
Economic data releases that moved the market
Scheduled economic releases, inflation prints, employment reports, retail sales, and manufacturing surveys, function as some of the most reliable near-term catalysts for daily index moves, since they directly feed into Treasury yield expectations and Federal Reserve policy outlooks.
A cooler-than-expected inflation report, for instance, tends to support bond prices and pressure yields lower, which in turn tends to lift the growth and technology names that carry the heaviest weighting in the S&P 500 and Nasdaq. A hotter print does the reverse, often weighing on the same names that benefit when yields fall.
Employment data carries similar weight, since a labor market that looks too strong can raise concerns about sustained inflation and a slower pace of rate cuts, while a softening labor report can be read as supportive of easier policy ahead. On days without a major scheduled release, markets often take their cues instead from corporate earnings and yield drift, which is consistent with the earnings-focused tone described earlier in this article.
Reading today’s close against the broader market mood
This session fits a theme that has defined much of the recent stretch: a handful of large, earnings-sensitive names carrying index-level gains while broader participation lags behind. The breadth gap between the NYSE and Nasdaq on the same day captures that tension well. It is not quite a contradiction of the index gains, but it is a reminder that record closes and uniform strength are not the same thing.
Sector rotation and rate sensitivity remain the two threads worth watching most closely from here. If Treasury yields stay contained and upcoming earnings confirm the growth outlook priced into mega-cap names, this kind of narrow-breadth rally has room to continue. If either of those breaks, breadth divergence tends to widen before index levels catch up.
— MarketCapLens
Turn today’s close into a clearer company-level view
Reading a single day’s index numbers tells you direction. Getting to the “why” behind them means checking sector concentration, market-cap weighting, and company-level data, which is exactly where our tools are built to help.
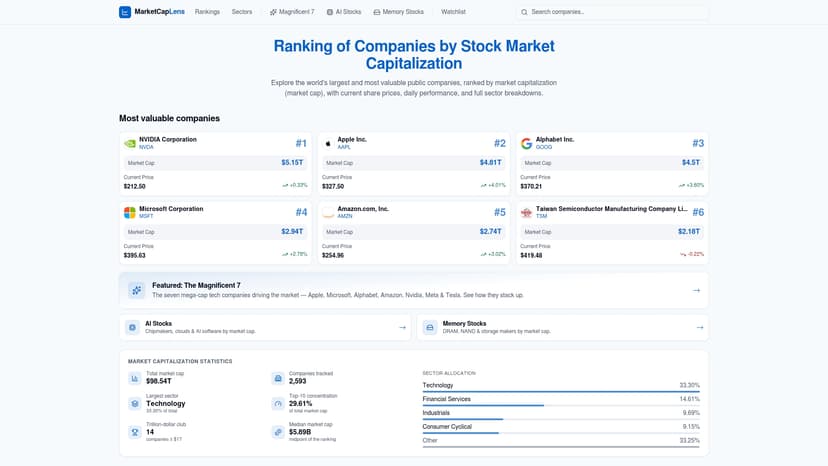
Our platform includes pricing and market-cap data refreshed multiple times daily, along with sector breakdowns and historical trend views designed to support detailed daily-to-company analysis.
- Start with our market-cap rankings to see which companies moved the index most.
- Use the market cap calculator to check how a company’s size compares with sector peers.
- Browse sector pages to see whether a move was sector-wide or driven by one or two names.
Check today’s rankings and see where the real action is beneath the headline.
FAQ
How is the market performing right now?
Daily performance depends on the specific session, but checking index closes alongside breadth, volume versus the 20-day average, and sector participation gives a fuller picture than the headline percent change alone. On a recent session, the S&P 500 and Nasdaq both closed at record highs while breadth diverged between exchanges, a pattern worth checking on any given day.
What percentage of Americans have over $100,000 in the stock market?
This figure is not publicly listed in the sources used for this article, so we are not able to state a reliable number here. Readers looking for household investment statistics should check a named government or financial-industry survey directly for the most current figure.
What is the 7% rule in stocks?
It is a risk-management rule used by some traders rather than a fixed market law, and it is not tied to any specific index or dataset referenced in this article.
How is the market performance today?
Checking today’s performance means looking at index closes and percent changes for the Dow, S&P 500, and Nasdaq, then layering in breadth (advancers versus decliners), volume versus the recent average, and which sectors led or lagged. Our sector pages and rankings update multiple times a day, which helps narrow a broad index move down to the specific companies driving it.
Sources
- US Stocks: S&P 500, Nasdaq reach record closing highs as focus pivots to earnings | ZAWYA
- Stock Market Today: Oct. 6 (The Motley Fool coverage)
- Analysis of divergent index and small-cap performance (The Guardian)
Recommended
For informational purposes only and is not investment advice. Do not rely on the facts, figures, ticker symbols, or other statements in this article — they may be incomplete, outdated, or incorrect, and we are not responsible for errors. See our disclaimer.